
BUSINESS
BlackRock Files PBIT to Put Bitcoin in Buffer Funds
BlackRock’s PBIT filing feeds Bitcoin into the $104.33 billion buffer-ETF channel, using IBIT options for an about 10% floor while crypto buffers hold only.

BlackRock filed on Oct. 19 for a Bitcoin ETF that sells part of the rally to buy a loss limit, using options tied to its $65.70 billion iShares Bitcoin Trust.
The iShares Bitcoin Managed Protection ETF, planned ticker PBIT, would be a 1940 Act fund. It would not hold bitcoin. The fee, the listing exchange, the upside cap and the launch date are all still blank.
BlackRock Files PBIT as a 1940 Act Buffer
iShares Trust submitted its October 19 registration statement as a Form 485APOS, listed as post-effective amendment No. 2,895, with BlackRock Fund Advisors as the adviser. The cover page checks the box for effectiveness 75 days after filing under Rule 485(a)(2), and the draft prospectus is dated for a blank day in 2027. Shares cannot be sold until that statement becomes effective.
ETF analyst James Seyffart called the product a buffer Bitcoin ETF, meaning holders give up some upside to get a measure of downside protection. He also wrote that this is BlackRock’s third Bitcoin ETF filing and that “It will be a 40 Act fund.”
BREAKING🚨 @BlackRock just filed for another Bitcoin ETF. This one will be a "buffer" Bitcoin ETF which will means it will offer downside protection but investors will give up some upside to get that protection. Ticker will be $PBIT. pic.twitter.com/302iMwn2fR
— James Seyffart (@JSeyff) October 19, 2026
That 1940 Act wrapper is the design choice that separates PBIT from the two Bitcoin products BlackRock already runs. Both the iShares Bitcoin Trust ETF (IBIT) and the iShares Bitcoin Premium Income ETF (BITA) tell investors they are not investment companies registered under the Investment Company Act of 1940. PBIT is being built as a series of iShares Trust on Form N-1A, and it intends to qualify as a regulated investment company.
WHAT THE PBIT FILING LEAVES BLANK
- Management fee: The fee table prints a blank for both the management fee and total annual fund operating expenses.
- Listing exchange: The ticker is PBIT; the exchange line is empty.
- Upside cap: Each tranche’s cap is set from market conditions when that tranche starts, with no number in the draft.
- Launch date: None is given, and a later amendment can move the 75-day window.
The filing is also candid about what the name does not mean. “There can be no assurance that the Fund will achieve its investment objective or that the Bitcoin Managed Protection Strategy will operate as intended, and investors may lose some or all of their money,” it says.
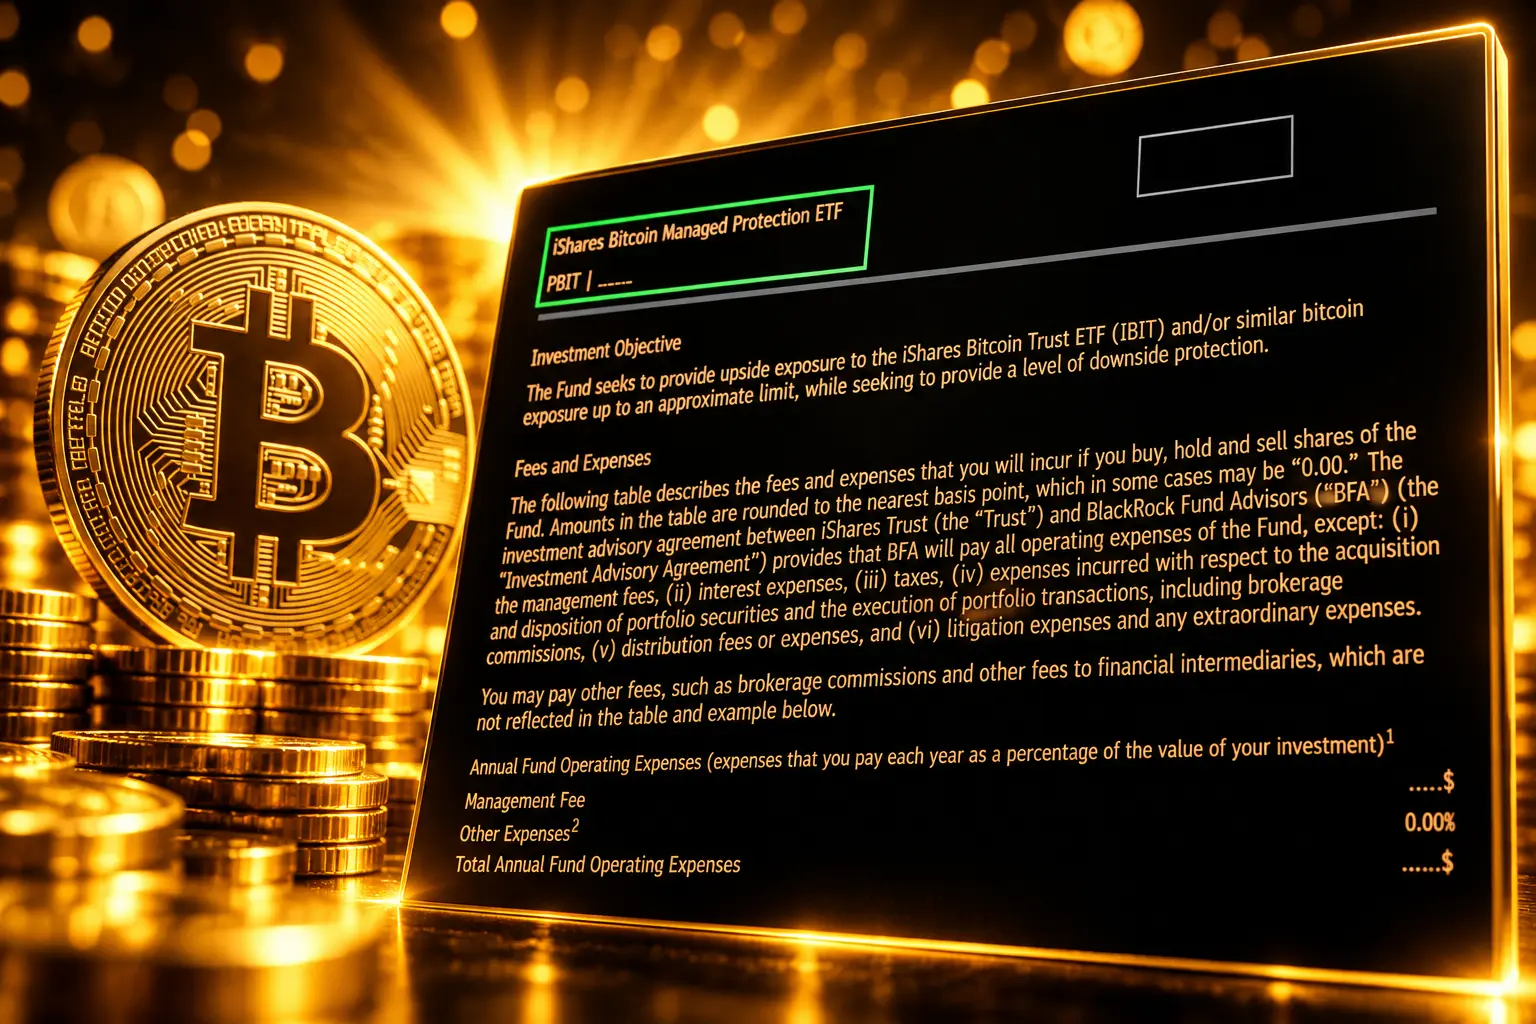
Three Call Spreads and a Floor That Moves
PBIT’s draft objective is blunt. The fund “seeks to provide upside exposure to the iShares Bitcoin Trust ETF (IBIT) and/or similar bitcoin exposure up to an approximate limit, while seeking to provide a level of downside protection.”
The Fund seeks to provide upside exposure to the iShares Bitcoin Trust ETF (IBIT) and/or similar bitcoin exposure up to an approximate limit, while seeking to provide a level of downside protection.
iShares Trust, Form 485APOS, filed Oct. 19, 2026
The method is an options overlay, not a bitcoin pile. The fund “does not invest directly in bitcoin or bitcoin exchange-traded products.” It plans to buy in-the-money call options on IBIT or similar bitcoin reference assets, sell out-of-the-money calls against them, and park the rest in cash, money market funds, short-term government debt and short-term investment-grade bonds, with the interest meant to help pay for the options.
Those calls are grouped in three overlapping tranches, typically staggered a month apart over a calendar quarter, so one sleeve expires and another opens each month. The fund expects to use FLEX Options, which are exchange-listed custom contracts, and it keeps discretion to hold more or fewer tranches. For each sleeve, the bought calls are typically struck at about 90% of the reference asset’s value when the position is opened. That sets an initial maximum loss exposure, which the filing calls the Floor, of about 10% before fees.
The Floor is not a promise that a shareholder’s loss stops at 10%. Because the fund holds several tranches at once, it “does not provide a fixed Tranche Protection Start Value, Floor or Tranche Cap Value.” If IBIT rises after a tranche starts, the bought calls still sit at the old strike, so the potential loss measured from the new price “will exceed the Floor.” Fees cut the upside and add to losses. Extreme volatility can shrink both the cap and the protection. The fixed-income book has its own risks and “do not ensure protection against losses.”
The Buffer Channel’s Crypto Sleeve Is $146 Million
Defined-outcome ETFs, the funds that sell a cap to buy a buffer, are already a large equity business. ETF Action’s buffer-channel tally for the week ended Oct. 17 put assets at $104.33 billion across 554 funds from 22 issuers, with $2,157 million of net inflows that week and $16,341 million year to date. FT Vest held $51.64 billion, or 49.50% of the channel. Innovator held $37.54 billion, or 35.98%.
Almost none of that money is in crypto. The same tally assigned 20 crypto buffer funds $146 million, with year-to-date outflows of $49 million and a one-year return of -14.86%. Equity funds in the channel held $104.11 billion.
BUFFER ETF ASSETS BY ASSET CLASS
| Asset class | Funds | AUM | YTD flows |
|---|---|---|---|
| Equity | 531 | $104.11 billion | $16,399 million |
| Crypto | 20 | $146 million | -$49 million |
| Commodity | 1 | $55 million | $4 million |
| Fixed income | 2 | $19 million | -$13 million |
| Channel total | 554 | $104.33 billion | $16,341 million |
That split is the second move inside the PBIT filing. BlackRock is not inventing buffered Bitcoin. It is trying to drag Bitcoin across the gap between a $104.33 billion equity habit and a $146 million crypto experiment. Cerulli Associates, in a November 2025 paper with Innovator, said defined-outcome ETFs could reach more than $334 billion by 2030 if home-office approvals keep widening. PBIT is how iShares would put Bitcoin on that same fact sheet, with a Floor a risk committee can read.
Calamos, First Trust and Innovator Got There First
Seyffart was clear that BlackRock is late to this structure.
Should add that this is nowhere near the first of its kind. There are defined outcome/buffered Bitcoin ETFs from Calamos, First Trust and Innovator. But when BlackRock does something (particular in this space) it tends to make a big splash.
James Seyffart, ETF analyst, on X
Calamos already runs protected Bitcoin funds at 100%, 90% and 80% protection over about a one-year outcome period, using FLEX options on bitcoin exchange-traded products and charging 0.69%. It also sells laddered protected Bitcoin ETFs that spread money across four quarterly series so a buyer is not tied to a single start date. John Koudounis, Calamos president and CEO, said the laddered funds map to traditional risk levels so bitcoin can sit inside existing portfolio frameworks.
Those funds, like PBIT, do not buy bitcoin. They buy options. They are 1940 Act funds. They already offer the defined protection levels that PBIT’s draft still describes as typical rather than fixed. The splash Seyffart expects is distribution, not invention: IBIT’s options market and the iShares shelf, dropped into a sleeve Calamos, First Trust and Innovator have been stocking without BlackRock’s name on the ticket.
THE BITCOIN PROTECTION CALENDAR
- Jan. 5, 2024: IBIT begins trading as BlackRock’s spot Bitcoin ETF.
- Oct. 14, 2025: Calamos launches laddered protected Bitcoin ETFs after a year of single-month protected series.
- June 9, 2026: BlackRock’s BITA income fund launches, writing calls against bitcoin and IBIT.
- Oct. 19, 2026: iShares Trust files PBIT as a 1940 Act managed-protection fund.
- Jan. 2, 2027: The 75-day clock on the Oct. 19 filing lands, unless the trust amends it.
A smaller IBIT position already cuts the same dollar risk without selling the rally. That is the simplest objection to a cap, and it is why a buffer has to clear a compliance test, not a trader’s test, to earn a ticket in a model book.
IBIT’s $65.70 Billion Still Dwarfs the Overlays
IBIT remains the base layer. BlackRock’s fund page lists $65.70 billion in net assets as of Oct. 19, 2026, with a NAV of $46.32, a 0.25% sponsor fee, and a year-to-date NAV return of -7.09% through Oct. 16. Holdings dated Oct. 16 show 802,987 bitcoin. The 52-week NAV range is $33.19 to $65.27. The benchmark, the CME CF Bitcoin Reference Rate – New York Variant, sat at $81,835.78.
The overlay experiment is much smaller. The iShares Bitcoin Premium Income ETF launched June 9, 2026, holds bitcoin and IBIT shares, writes calls, and charges 0.65%. On Oct. 19 it had $97.3 million in net assets and a NAV of $61.55. Its distribution rate was 14.24% as of Oct. 16. Four months of income packaging, on top of the largest spot Bitcoin ETF, produced a fund that is still a rounding error next to IBIT.
BLACKROCK’S THREE BITCOIN PRODUCTS
| Fund | Status | Holds | Fee | Net assets (Oct. 19) |
|---|---|---|---|---|
| IBIT | Trading since Jan. 5, 2024 | Bitcoin | 0.25% | $65.70 billion |
| BITA | Trading since June 9, 2026 | Bitcoin and IBIT, writes calls | 0.65% | $97.3 million |
| PBIT | Filed, not trading | Options on IBIT; no bitcoin | Not disclosed | None |
PBIT would not replace IBIT. It would sit beside it as the third way iShares packages the same reference asset: full beta, income with a partial cap, and a managed Floor. BITA’s $97.3 million is the caution inside that lineup. Options overlays on Bitcoin have not gathered IBIT-scale cash, even with BlackRock’s name on them. PBIT asks the same distribution machine to sell a more complicated trade, with a blank fee, to the advisers who would not buy the unhedged trust.
Where the Next Bitcoin Allocation Has to Sit
Buffer ETFs live in model portfolios because the outcome period, the cap and the buffer can be written on a single page a home office can approve. IBIT gave those offices a ticker for bitcoin. It did not give them a loss budget. A 1940 Act series that talks about a Floor of about 10% per tranche, even with all the caveats in the prospectus, is the format that channel already buys in stocks.
That is also why the product can frustrate anyone who wanted Bitcoin for the uncapped move. The sold calls are there to pay for the bought calls. In a sharp rally the fund “will not fully participate in increases in the Bitcoin Reference Asset and may significantly underperform it, while still bearing losses that may be substantial.” Sizing IBIT down does the risk job without that ceiling. PBIT is for the book that is not allowed to size IBIT up.
BlackRock is still not stretching the crypto list. Seyffart noted the firm has Bitcoin and Ethereum products and no other coins, even as other issuers have listed funds tied to XRP, Solana and Dogecoin. PBIT does not add a new asset. It adds a new risk sleeve on the asset iShares already dominates, and it may, if the options reference IBIT as planned, put more activity through the same trust that already holds 802,987 bitcoin.
The 75-Day Clock and a Blank Fee Line
Counted from Oct. 19, 2026, 75 days lands on Jan. 2, 2027. That is the window the cover page selects, not a listing date, and the trust can file again and move it. Until then the market is watching three blanks that will decide whether this sleeve fills: the management fee, the first tranche caps, and the exchange.
Calamos already charges 0.69% for a defined one-year outcome. BITA charges 0.65% for income. IBIT charges 0.25% for the raw coin. PBIT has to land in that spread with a Floor that is typical, not fixed, and with three overlapping tranches that will not match any one investor’s holding period. If the fee comes in cheap and the iShares models pick it up, the $146 million crypto buffer sleeve finally gets a shelf. If it prices like the other overlays, it risks looking like BITA: a clever wrapper on a giant trust, still waiting for the money that already bought the unhedged shares.
Disclaimer: This article is news reporting and analysis of a registration filing, and it is for information only. It is not investment advice, tax advice, or a recommendation to buy, sell, or hold PBIT, IBIT, BITA, any Calamos fund, bitcoin, or options. Readers should consult a licensed financial adviser and, where tax treatment matters, a qualified tax professional before acting on any fund or digital-asset product, because defined-outcome terms, fees, and protections can change and can fail to match the outcomes described in a draft prospectus. Figures and statuses here reflect the cited fund pages, the Oct. 19, 2026 Form 485APOS, and the Oct. 17, 2026 buffer-channel tally, and they may change as later amendments, launches, or market moves arrive.

Cook Hands Democrats the House as Crypto’s Bill Stays Dead

Wicker’s Broken Bed Was the Short Story’s Punch Line

Nvidia’s $500 Billion Financing Plan Draws a $180 Sell

Maserati Bets the Grecale V6 Can Fill Porsche’s Gap

EV Cable Theft Follows the Old Railway Copper Playbook

Aramco Crash Kills 14 Two Days After Oil Restart

Salah Captained Egypt to Their First World Cup Win

Zelda’s 40th Switch 2 Ships Without a Zelda Game

Apple Labor Day Deals Hide June’s Memory Price Hike

Palworld 1.0.4 Adds Palpedia Search After the 1.0 Launch
-
 BUSINESS4 months ago
Aramco Crash Kills 14 Two Days After Oil Restart
-
 NEWS5 months ago
Salah Captained Egypt to Their First World Cup Win
-
 GAMING2 months ago
Zelda’s 40th Switch 2 Ships Without a Zelda Game
-
 NEWS2 months ago
Apple Labor Day Deals Hide June’s Memory Price Hike
-
 GAMING2 months ago
Palworld 1.0.4 Adds Palpedia Search After the 1.0 Launch
-

 NEWS4 months ago
El Niño Puts Israel’s Needed Winter Rain on a Flood Clock
-

 BUSINESS8 months ago
BAE’s 60-Year Saudi Franchise Now Runs Through Taif
-

 BUSINESS8 months ago
Egypt Bets EGP 638 Billion Can Open Sinai to Investors