
BUSINESS
Philadelphia Votes In a City IRA States Already Run
Philadelphia approved PhillySaves, a city auto-IRA for workers without a workplace plan, copying state programs that now hold more than $3.4 billion.

Philadelphia voters approved PhillySaves on May 19, 2026, with 170,868 yes ballots, a 78.4% share. The city auto-IRA will enroll private-sector workers whose employers offer no retirement plan, then take 3% to 6% of pay unless they opt out.
The vote copies a state model Oregon opened in 2017. State auto-IRAs now hold more than $3.4 billion, and two other cities already authorized similar programs, then stood down when their states built their own.
Philadelphia’s 78% Vote for a City IRA
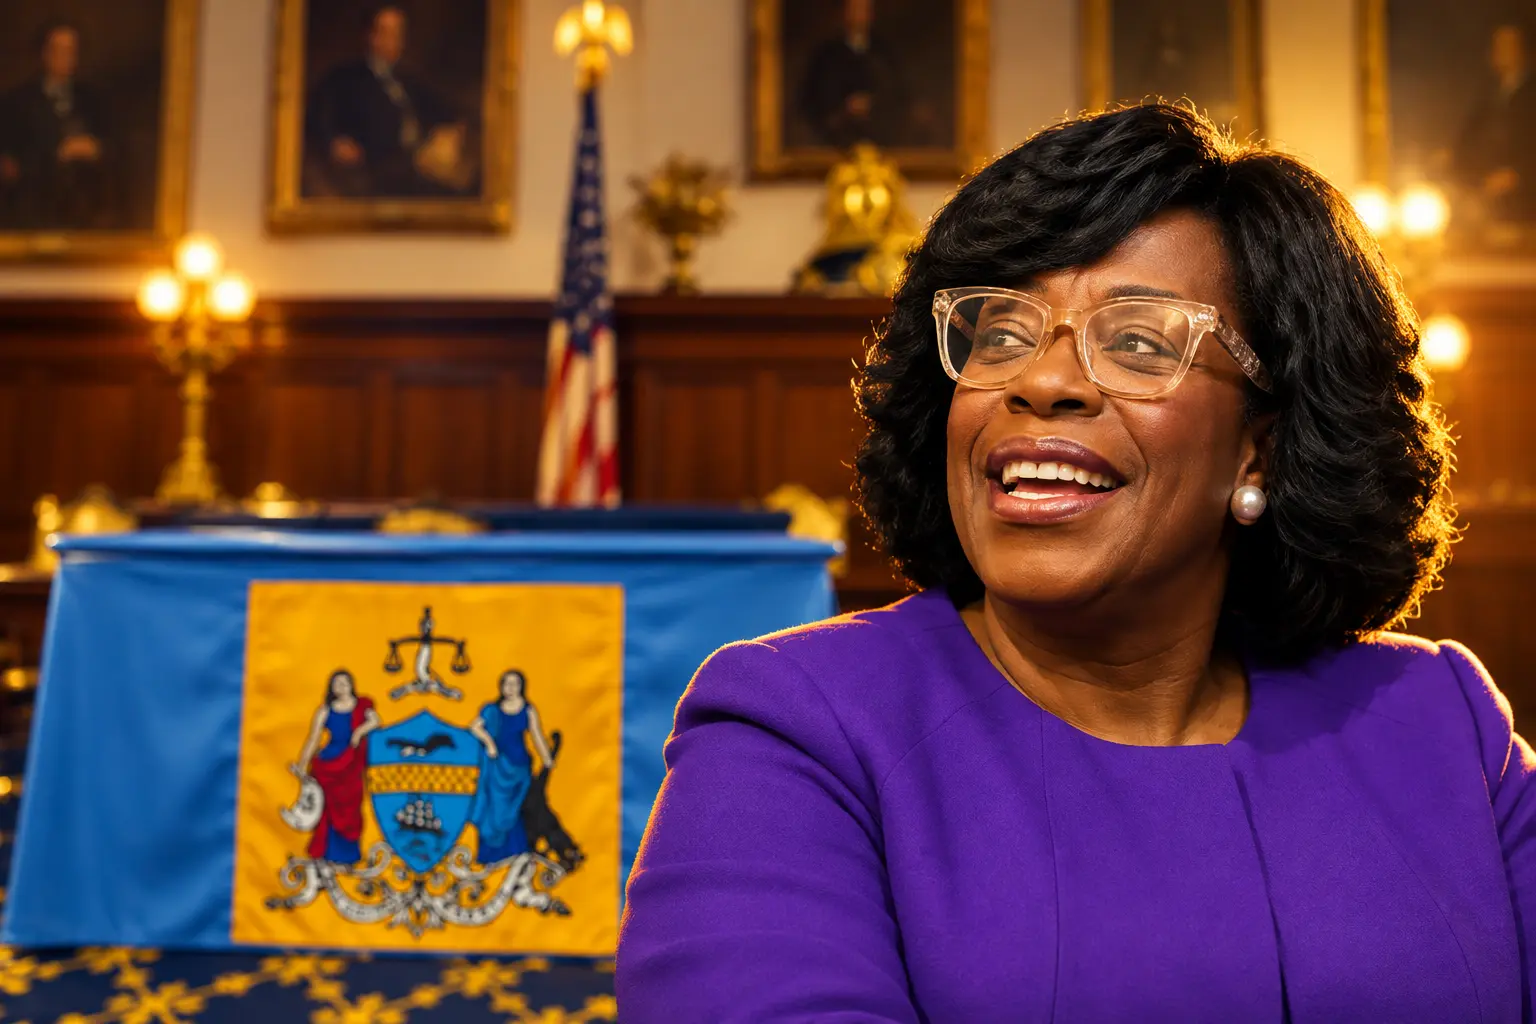
Mayor Cherelle L. Parker signed two bills establishing PhillySaves in January 2026, after City Council passed them in December 2025. Council President Kenyatta Johnson sponsored the package with Councilmember Mike Driscoll. The May ballot question then created the Philadelphia Retirement Savings Board that will run it.
Unofficial returns tallied 170,868 yes votes and 47,085 no votes, or 217,953 ballots in all. That 78.4% yes share cleared the simple majority the charter change needed. Pew Charitable Trusts has estimated about 208,000 private-sector workers in the city have no workplace retirement plan. Johnson used that gap when he asked voters to lock the board into the charter.
THE MAY VOTE AND THE BOX IT BUILT
- Yes share: 170,868 ballots, 78.4% of 217,953 votes cast on the question.
- The board: Nine members, four named by the mayor, four by the Council president, and one by the City Controller.
- The default: A board-set rate between 3% and 6% of wages, taken by payroll unless the worker opts out.
- The clock: First deductions are scheduled by July 1, 2027.
Parker has worked on retirement access in the city for a decade, and she tied the bills to later pressure on city services.
This is an issue that I have cared about deeply and worked on with many other stakeholders for 10 years. It is a very big deal for the City of Philadelphia, and for our residents because it can reduce future strain on social services.
Cherelle L. Parker, Mayor of Philadelphia, at the PhillySaves bill signing
Pew’s John Scott, who directs its retirement savings project, told the same signing that 35% of Philadelphia residents over 65 live on about $15,000 a year, while households with retirement income have a median of nearly $58,000. PhillySaves does not promise the second number. It opens a payroll pipe for people who never had one at work.
State Auto-IRAs Hold More Than $3.4 Billion
Oregon launched the first of these programs in October 2017 with $121,800 in assets and 993 funded accounts, according to Georgetown University’s Center for Retirement Initiatives. The same tracker says assets across 15 reporting state auto-IRAs had grown to more than $3.4 billion by September 30, 2026, with funded accounts above 1.4 million by August 31, 2026.
CalSavers holds 57% of those assets. OregonSaves holds 16%, and My Illinois Savings holds 11%. Those three books are 84% of the money. By account count, CalSavers has 46%, OregonSaves 13%, and Illinois 11%, or 70% of funded accounts. Twelve of the 15 reporting auto-IRA programs opened in 2022 or later, so most of the pile is still young.
Pew’s August 2026 update of its state map said that by June 2026, 15 states had active auto-IRA programs, with more than 1.3 million participating workers and upward of $3 billion saved. Two other states and Philadelphia had passed enabling laws and were still building. Georgetown’s state roster lists 22 enacted state programs and three city efforts. New York City and Seattle are the other two cities, and neither is moving forward as a standalone system.
OregonSaves After Nine Years on the Books
If PhillySaves works like the programs it is copying, the honest preview is not a million-dollar nest egg. It is a small, sticky account that some workers will drain.
The OregonSaves monthly dashboard as of July 31, 2026, put assets at $516 million across 156,691 funded accounts. The average funded balance was $3,292. Workers who still had money in the plan were sending $214 a month on average, with a median of $152, at a 7.0% average savings rate. The first-30-day opt-out rate since inception was 26.5%.
Average Balances in the Low Thousands
Illinois, which reports under the My Illinois Savings name, posted a similar scale on its August 2026 treasurer dashboard: $372 million in assets, 177,847 funded accounts, and an average funded balance of $2,092. The average monthly contribution was $169. A full-withdrawal rate of 26.53% sat beside that balance, a different measure from Oregon’s 26.5% early opt-out, and a reminder that getting people in is not the same as keeping the money in.
TWO STATE LEDGERS PHILLY IS COPYING
| Program | Snapshot | Assets | Funded accounts | Average balance |
|---|---|---|---|---|
| OregonSaves | July 31, 2026 | $516 million | 156,691 | $3,292 |
| My Illinois Savings | August 2026 | $372 million | 177,847 | $2,092 |
Oregon’s running totals also show how leaky the pipe is. Savers had contributed $639 million since inception and withdrawn $263 million. The dashboard counted 78,045 accounts with a withdrawal. Payroll-contributing accounts, at 207,787, ran ahead of funded accounts, which means a slice of the file had no balance on the books.
Registered Employers and Actual Payroll Files
The employer file is the other half of the preview. Oregon listed 36,136 registered employers and 51,415 exempted ones. Only 8,525 registered shops had actively submitted payroll in the prior three months. A city program can print an enrollment rule and still watch a large share of covered firms sit on the file without sending money.
PhillySaves will face that same friction in a denser labor market, with more very small shops and a board that has not yet named a recordkeeper. The state ledgers do not say the model fails. They say its typical funded account, after years of automatic deductions, is still measured in a few thousand dollars.
The City Plans New York and Seattle Abandoned
Philadelphia is not the first city that tried to do this. Georgetown’s state roster says New York City’s auto-IRA will no longer be implemented because New York State enacted its own program, and that Seattle’s plan is on hold pending state action. Washington later passed Washington Saves, which is scheduled to launch in July 2027, the same month PhillySaves is aiming to take its first deductions.
Pennsylvania still has no statewide auto-IRA. That vacancy is why a city law could become an operating program instead of a clause that gets folded into a state board. AARP’s Public Policy Institute found that 42 percent of Pennsylvania private-sector workers ages 18 to 64 in 2022 were at businesses that offered no retirement plan, about 2,034,729 people. State Treasurer Stacy Garrity has pushed Harrisburg to fill that gap and has described the uncovered group as everyday workers, including mechanics and waitresses, who still have no payroll way to save.
HOW THE CITY MODEL GOT HERE
- October 2017: Oregon opens OregonSaves, the first state auto-IRA.
- July 2019: California begins statewide CalSavers enrollment.
- 2025: New York opens a state auto-IRA, and New York City’s city program is shelved.
- May 19, 2026: Philadelphia voters approve the Retirement Savings Board for PhillySaves.
- July 1, 2027: PhillySaves is scheduled to start payroll deductions, and Washington Saves targets the same month.
The Greater Philadelphia Chamber of Commerce, AARP Pennsylvania, Pew, and the Northeast Philadelphia Small Business Alliance backed the city bills. A city mandate is still a workaround for a state that has not passed one. If Harrisburg later opens a Pennsylvania auto-IRA, PhillySaves could face the same absorption that ended the New York City version. Until then, other Pennsylvania cities have a live template sitting on Broad Street.
Who Must Join PhillySaves, and Who Can Skip It?
Covered employers are Philadelphia businesses and nonprofits that have operated at least two years, have at least one employee, and do not already sponsor a retirement plan. Those shops must enroll eligible staff and run the deductions. They do not put in company money. A firm that starts its own qualifying plan steps out of the mandate.
THE COVERAGE RULES ON THE BOOKS
- The workers: Employees of covered Philadelphia shops with no workplace plan, auto-enrolled unless they opt out.
- The account: An IRA the employee owns, with a choice of traditional or Roth, funded only by that worker’s pay.
- The default rate: Set by the board inside a 3% to 6% band; workers can change the rate or stop.
- The excluded: Sole proprietors and other self-employed people, unless the board later extends coverage.
- The off-ramp for firms: Offer a qualifying employer plan, and the PhillySaves duty does not apply.
Self-employed people are a large share of the uncovered population in any city, and they are outside this first version. The board may revisit that. For now the program is a payroll tool, which means it only reaches people who have an employer willing, or required, to touch a paycheck.
No Employer Match, by Design
State auto-IRAs bar employer contributions so the accounts stay IRAs and do not become employer plans under federal pension rules. PhillySaves follows that line. Shops facilitate enrollment and deductions. They do not match, they do not pick funds, and they do not take on a pension promise.
Scott put the employer pitch in cost terms at the January signing, saying Philadelphia businesses would, at no cost to them, be able to attract and retain workers by offering a retirement savings plan, and that taxpayers would benefit if more residents saved enough to lean less on assistance later. That is the political bargain: a mandate with no company match, sold as free for the shop and useful for the city budget.
The shop still has work. Someone has to add a deduction code, keep the roster current, and answer staff who see a new line on a stub. Law-firm notes on the ordinance warn that employers without a plan may face penalties once the program is live, though the board has not posted a fine schedule. For many small firms, the cleaner exit is to open a 401(k), which can take larger annual contributions and a company match, and which also satisfies the mandate.
The product on the worker side is easy to misread as a city pension. It is not one. Pay goes into an IRA the employee owns, the worker takes the market result, and Philadelphia adds no defined-benefit liability. That distinction will matter the first time a paycheck shrinks and a new hire asks who guaranteed the balance.
July 2027 Starts the Payroll Clock
Approval put a board on the charter. It did not pick a recordkeeper, a default percentage inside the 3% to 6% band, a target-date fund, or the notices employers will have to hand out. Those choices now sit with nine appointees and whatever private administrator they hire, the same vendor model Oregon runs with firms such as Vestwell and Ascensus.
The fund menu is the decision the vote did not settle. A plain target-date mix would track the state programs. A screened book would turn a payroll IRA into a city investment policy. Until that paper is public, workers are being signed up for an account whose default they have not seen.
A smooth launch still depends on boring things: a one-page opt-out, a helpline that answers, and a payroll file small shops can submit without buying new software. Oregon’s gap between 36,136 registered employers and 8,525 that actually sent pay in a recent quarter is the operational risk Philadelphia now owns. The city also has to explain, in plain language, that this deduction is optional, reversible, and not a municipal pension.
If the board hits July 1, 2027, PhillySaves will start taking 3% to 6% from covered paychecks and posting it to IRAs the workers own. The state books say a lot of those accounts will stay open, a quarter of new savers will leave in the first month, and the average funded balance after years of this design will still look like a few thousand dollars. That is the machine Philadelphia just voted to plug in.
Disclaimer: This article is news reporting and analysis of a municipal retirement-savings program, and it is for information only. It is not investment advice, tax advice, or a recommendation to join, opt out of, or contribute to PhillySaves or any IRA, 401(k), or other account. Readers who are deciding how to save, how much to contribute, or how a payroll deduction would affect take-home pay should consult a qualified financial adviser or tax professional who can review their own situation. Vote totals, program rules, asset figures, and the July 1, 2027 launch target reflect the official and research sources cited here and may change as the board writes operating rules and names a vendor.

One UI 9.5 Beta Puts the Galaxy S26 on Last Year’s Clock

DBS Puts a 24/7 USDC Window Inside the Bank

European Startups Head for $81 Billion as First Checks Shrink

US Stocks Lost $1.3 Trillion Before Nvidia’s Beat

Home Depot Bets on Finance Chief Richard McPhail as CEO

Aramco Crash Kills 14 Two Days After Oil Restart

Salah Captained Egypt to Their First World Cup Win

Zelda’s 40th Switch 2 Ships Without a Zelda Game

Apple Labor Day Deals Hide June’s Memory Price Hike

El Niño Puts Israel’s Needed Winter Rain on a Flood Clock
-
 BUSINESS5 months ago
Aramco Crash Kills 14 Two Days After Oil Restart
-
 NEWS6 months ago
Salah Captained Egypt to Their First World Cup Win
-
 GAMING2 months ago
Zelda’s 40th Switch 2 Ships Without a Zelda Game
-
 NEWS3 months ago
Apple Labor Day Deals Hide June’s Memory Price Hike
-
 NEWS4 months ago
El Niño Puts Israel’s Needed Winter Rain on a Flood Clock
-

 GAMING2 months ago
Palworld 1.0.4 Adds Palpedia Search After the 1.0 Launch
-

 NEWS4 months ago
Saudi Visa Routes Split Nigerian Travelers Into Two Speeds
-

 BUSINESS9 months ago
BAE’s 60-Year Saudi Franchise Now Runs Through Taif