
NEWS
Haatch Backs Perry AI’s $2.2 Million Fund-Memory Bet
Haatch led Perry AI’s $2.2 million seed, a bet that fund-specific legal memory beats generic AI in private capital.

Perry AI raised $2.2 million on November 18, 2026, in an oversubscribed seed led by Haatch. The London legaltech sells software that stores a private capital fund’s rights, obligations and past negotiation positions, then lets AI agents work from that record.
The check is a seed-sized wager in a market that already poured billions into legal AI this year. Generic tools can summarise a contract. They cannot, the founders argue, remember what this fund promised three deals ago.
$2.2 Million Against a $2.34 Billion Quarter
Legalcomplex’s Spark dataset put first-quarter 2026 legaltech funding at $2.34 billion across 103 deals. Relativity, Legora and Harvey took $720 million, $550 million and $200 million, or 63% of the money. The other 100 deals shared $870 million, and the median round was $1 million.
Perry’s seed sits above that median and nowhere near the three names that soaked up the quarter. Seed rounds also outnumbered growth rounds, 46 to 44, for the first time since the first quarter of 2024. A lot of AI-native legal startups are raising small checks while later-stage cash piles into a few platforms.
THE Q1 2026 LEGALTECH SPLIT
- Headline total: $2.34 billion went into 103 legaltech deals in the first quarter of 2026, per Legalcomplex Spark.
- Three-firm share: Relativity, Legora and Harvey combined for $1.47 billion, about 63% of the quarter.
- The rest: $870 million was spread across 100 other deals, with a $1 million median.
- Stage mix: 46 seed rounds beat 44 growth rounds, a crossover Spark had not seen since early 2024.
Haatch is built for that lower tier. The Stamford and London firm backs UK B2B software at pre-seed and seed, and its investor materials list EIS tickets of £500k or more beside SEIS tickets of up to £250,000. It completed 68 investments in 2025, on its own figures, and is not in the business of writing Harvey-scale cheques.
Fred Soneya, Haatch co-founder and general partner, led the round with Marwa Ebrahim. He is placing the firm’s bet on depth, not on a general legal chatbot.
The biggest wins in AI will go to companies that go deep in markets where the stakes are high and generalist tools fall short. Private capital legal work is a textbook example.
Fred Soneya, co-founder and general partner, Haatch
Antler is doubling down after Patel went through its London founder residency, with Adam French, Hannah Leach and Sarah Finegan named on the round. Syncorp Ventures and Arāya Ventures joined, with Rupa Popat and Martin Carruthers listed for Arāya, plus US and international angels.
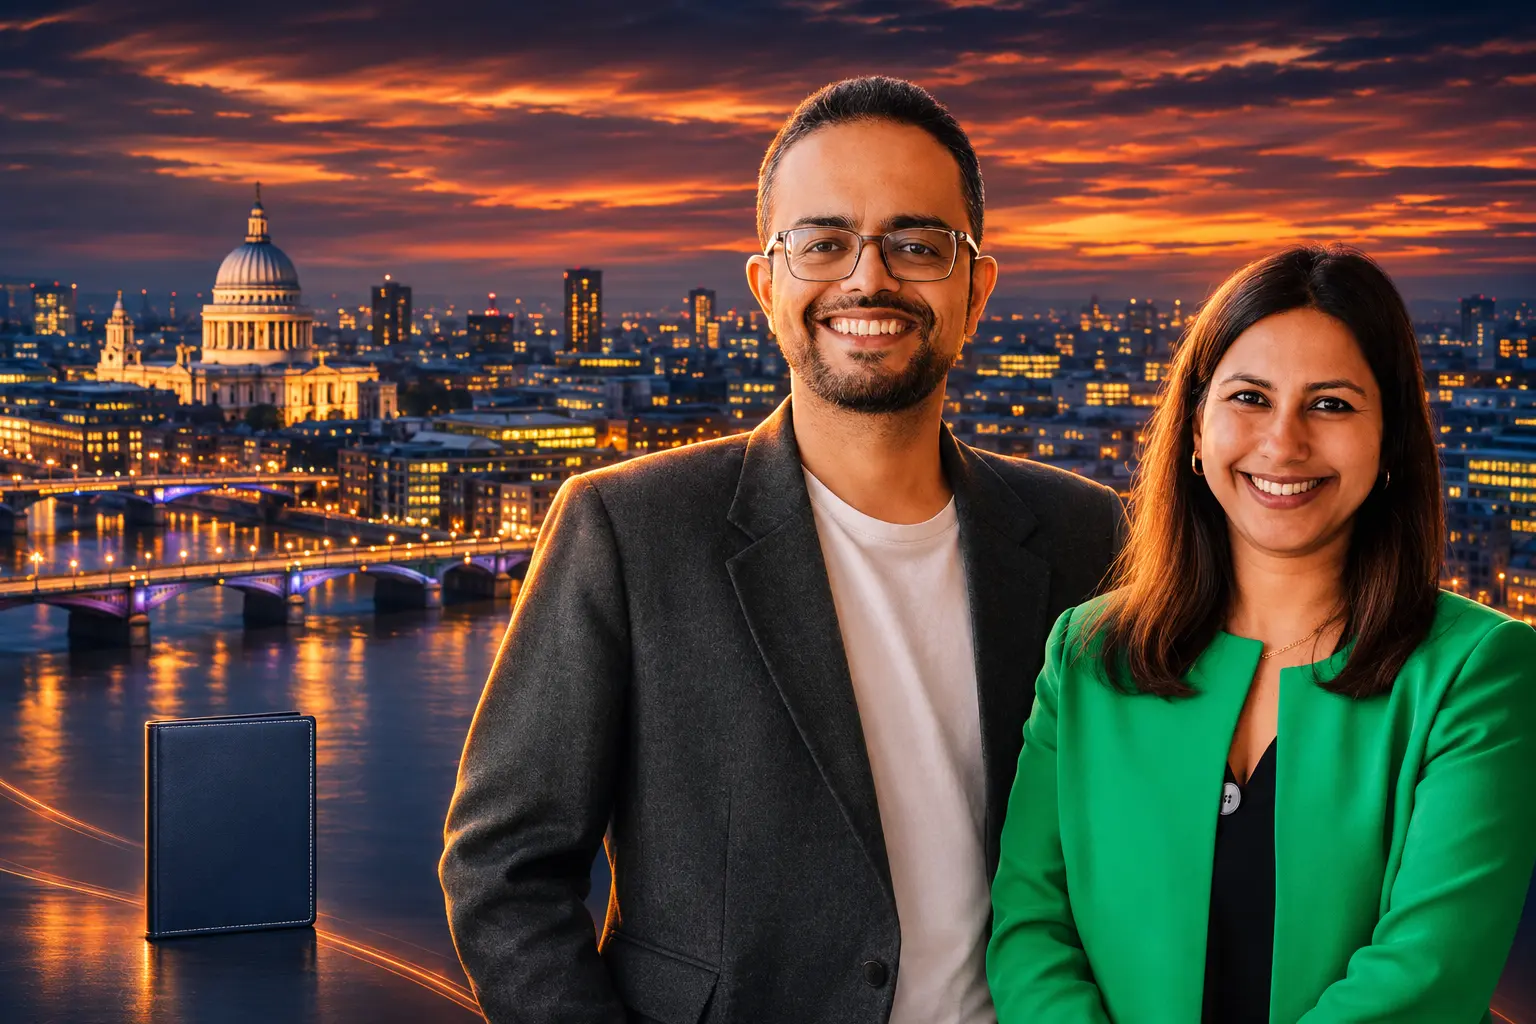
Two Funds Lawyers Left Practice to Build Perry AI
Shashwat Patel, chief executive, and Vaneesa Agrawal, chief product officer, are a husband-and-wife pair of former funds lawyers who started Perry AI in 2025. The company still lists five people on LinkedIn.
Patel spent 15 years as a private equity and funds lawyer at Debevoise & Plimpton and Simmons & Simmons in London, where he headed the India group. His client list included BlackRock, Brookfield, Invesco, Clayton Dubilier & Rice and HarbourVest. He is qualified in New York, England and India, holds an LL.M. from Columbia Law School as a Harlan Fiske Stone Scholar, and began at Amarchand & Mangaldas in Mumbai.
Agrawal, an NYU School of Law graduate, spent more than 12 years as a funds lawyer and then built a venture capital boutique that handled 75 deals and reached a top-tier Legal 500 ranking within three years. Soneya’s line that the pair have spent nearly three decades between them on this work is his arithmetic on those two careers, not a third clock.
Patel’s pitch is the fear that sits under a close, not the summarising of a PDF. He said every deal had the same undercurrent, a scramble against the clock in a regulated market, with the worry that a side letter promise, a consent, a preemption right or an MFN obligation from three deals back had been missed.
Generic AI can’t take that fear away, because it doesn’t know the fund. Perry AI does. It remembers every position a fund has taken and acts on it, so legal teams can move fast and still sleep at night.
Shashwat Patel, co-founder and chief executive, Perry AI
Sarah Finegan, associate partner at Antler, which says it has backed more than 2,000 startups, called private capital legal operations a market generalist software has never served well, still run on manual, legacy workflows. That is the gap a five-person shop is now raising to fill in the US and Asia as well as the UK and Europe.
What a Fund Legal OS Is Meant to Remember
Perry’s public site frames the product as a legal operating system for private capital, an AI layer across formation, deal execution and portfolio governance. In-house lawyers and outside counsel are supposed to work from one live record of rights, obligations and commitments, rather than from inboxes and prior-deal folders.
The company says funds already on the platform manage more than $1.5 billion across more than 1,000 portfolio companies, with customers and pipeline in the UK, Europe, the US and India. It also says customers report working 90% faster on workflows, a figure it treats as separate from signing times on live deals, which it says have fallen from 84 days to 13 days.
Those customer numbers are Perry’s own. They are the traction Haatch is underwriting, and they are not a third-party audit of every file on the system.
THE FUND WORKFLOWS ON THE PLATFORM
- Negotiation review: Agents read new papers against the fund’s historical positions rather than against a generic playbook.
- Side letter terms: The product extracts and aggregates terms across side letters so scattered promises sit in one place.
- MFN workflow: Most-favored-nation elections are meant to run in a single workspace instead of a spreadsheet chase.
- Operational handoff: Language in LPAs and side letters is turned into tasks the fund can track after signing.
- Shared record: In-house teams and external advisers work from the same continuously updated file, the company says.
Named users on the site are already mixing fund and firm seats. Max Neuberger, general counsel at Entrepreneurs First, said the product matched known and unknown uses and that the team was energised to fix the problems. Sarah Yen, deputy general counsel at the same firm, said work that took a senior lawyer 30 to 45 minutes, or a junior two hours, was largely done in 10 to 15 minutes. Rohan Paliwal, a senior associate at Stakeboat Capital, said Perry’s grasp of private equity deal structures went beyond template filling and freed the team for commercial judgement calls.
Fund lawyers and operations staff are the actual buyers. A general counsel who already pays for a firm-wide Harvey seat will not move for a summariser. They might move for a system that already knows this fund’s MFN grid and last-round fallbacks. That is also why a seed-stage memory layer still has to win trust against tools those same lawyers already have on their laptops.
The Formation Bill ILPA Wants Capped
Perry says a typical private equity deal still costs hundreds of thousands of dollars in legal fees and can take up to six months to close. That is the company’s market claim, and it is the pain the seed is supposed to price against. Formation is a second, related bill, and limited partners have started to push back on it in public.
The Institutional Limited Partners Association, in guidance dated May 14, 2026, asked the industry to cap of 5 basis points or $10 million, whichever is lower, on organizational expenses borne solely by LPs, and to split any overage 50-50 between GP and LP. On ILPA’s own arithmetic, $10 million is 5 basis points on a $20 billion fund. An Albourne Partners survey of almost 2,000 funds, cited in that debate, found median organizational expense caps moving from about 20 basis points in 2019-2021 to about 25 basis points in 2024-2025.
ILPA’S FORMATION COST RULES
| Item | Figure |
|---|---|
| Proposed LP-only cap | Lower of 5 bps of target AUM or $10 million |
| $10 million as 5 bps | A $20 billion fund |
| Overage split | 50% GP, 50% LP |
| Albourne median cap, 2019-2021 | About 20 bps |
| Albourne median cap, 2024-2025 | About 25 bps |
Scott Ramsower, ILPA board chair and head of private equity funds at the Teacher Retirement System of Texas, said partnerships in the industry often start with fund formation, which is exactly the work Perry now lists as a next module. If LPs are capping what they will pay outside counsel to stand a fund up, a shared draft-and-track layer is one of the few ways a GP can cut the bill without cutting the advice.
Deal execution and formation are different invoices. Perry’s “hundreds of thousands” line is about transactions. ILPA’s $10 million cap is about the cost of creating the vehicle. Both are legal time billed against private capital, and both are on Perry’s product map.
Harvey and Legora Still Dwarf the Check
The generalists Soneya is betting against did not stand still in 2026. Harvey’s first-quarter round in the Spark set was $200 million. It later added another $550 million. Legora’s first-quarter round was $550 million, and it later added another $550 million. Those later cheques are a different quantity from the Q1 table, and they are the war chests a vertical seed has to live beside.
Perry is not the only funds-lawyer startup in the lane. Intelligent Legal Solutions, built by former Goodwin lawyers, raised a $3 million seed in March 2026 around side letters, MFN elections and post-close private equity workflows. The pack is real. So is the gap in capital.
SEED MONEY NEXT TO THE LEGAL AI GIANTS
| Company | 2026 capital in view | Job it sells |
|---|---|---|
| Perry AI | $2.2 million seed, November 18 | Fund-level legal memory for private capital |
| ILS | $3 million seed, March | Side letters, MFN, post-close fund work |
| Harvey | $200 million in Q1, then $550 million | Generalist legal AI for firms and in-house teams |
| Legora | $550 million in Q1, then $550 million | Generalist legal AI |
| Relativity | $720 million debt facility in Q1 | Large-scale legal platform finance, not a seed peer |
A GC who already has a generalist seat can still buy a vertical layer if the vertical layer holds the fund. That is the opening. The closing risk is obvious from the table: Harvey or Legora can add fund memory later, with more salespeople and more security paperwork, and the seed’s head start becomes a feature list on someone else’s roadmap.
Kelsey Chase’s Second Pass at Deal Data
The US angel named on the round is Kelsey Chase, founder of Aumni, the investment analytics company later bought by J.P. Morgan. Chase started as a corporate lawyer at Wilson Sonsini and DLA Piper, then spent years extracting legal and economic terms from private market agreements so funds could see what they had actually signed.
Aumni’s pitch, before the bank acquired it in 2023, was that the rights that matter in venture and growth deals are buried in the documents, and that a product which reads those documents can change how managers monitor a portfolio. Perry is a different company, with a different buyer and a live workspace rather than a pure analytics feed. The through-line is the same stubborn object: the side letter, the MFN, the negotiated exception that never makes it into the admin system.
Chase’s cheque is not a random celebrity angel line. It is a second attempt, by someone who already productised private-market legal data, to back a team that wants that data to act inside the next deal, not only to sit in a dashboard. If the bet fails, it will fail in a category she already knows is hard to keep alive inside a larger institution.
The Seed Has to Stretch to America and Asia
Perry says the new money will fund expansion in the US and Asia while it deepens the UK and Europe. Patel scheduled meetings in New York from November 15 through November 20 with fund partners, general counsel, lawyers and operators, a trip that overlapped the announcement. The product roadmap beyond live deal execution includes fund formation, secondaries, fund transfers, LP reporting, MFN tracking and co-investment allocation, some of which the company says are already live.
THE SEED CALENDAR
- 2025: Patel and Agrawal found Perry AI in London after leaving funds practice.
- November 15, 2026: Patel opens a run of New York meetings with fund partners and general counsel.
- November 18, 2026: The company closes the $2.2 million oversubscribed seed led by Haatch, with Antler, Syncorp Ventures, Arāya Ventures and Chase among the backers.
Five people, a $2.2 million seed, and a map that now includes the US, Asia, formation, secondaries and LP reporting is a lot of surface area. The Haatch thesis only works if the memory layer stays deep enough that a fund will not swap it for a generalist add-on, and if outside counsel will type into a shared record that makes some of their hours disappear.
The next test is not another press line about legal AI. It is whether a fund that already ran one live deal from 84 days to 13 will run the next one on the same system, and whether a US counsel will trust a London seed with the file that contains every side letter the LP roster cares about.
Frequently Asked Questions
What is an MFN clause in a private fund?
A most-favored-nation clause lets a limited partner claim the benefit of a better economic or governance term the fund later grants another LP, which is why counsel has to harvest every side letter and run elections after each close. Perry lists MFN workflow as a native module because that election work is repetitive, easy to miss, and expensive when it is done by hand across a large investor base.
What counts as an organizational expense in private equity?
Organizational expenses are the legal, administrative and compliance costs of forming the fund, usually directed by GP-chosen counsel and charged to LPs, covering the LPA, subscription documents, filings and side letter negotiation. ILPA’s 2026 guidance treats those costs as a partnership problem, not a software category, which is why a drafting and tracking tool is being sold into a budget LPs are trying to cap.
Does Perry AI use client files to train its models?
The company says client data is never used to train models and is never shared between customers. That claim sits beside the product’s other promise, a shared live record for in-house lawyers and external advisers, and it is the assurance a regulated fund will demand before it loads every side letter into a startup’s database.
Is Perry AI meant to replace a fund’s outside counsel?
No. The company sells to private capital funds and to the law firms that already advise them, and it asks both sides to work from the same continuously updated record. Named users already include in-house lawyers at Entrepreneurs First and a senior associate at Stakeboat Capital, which is a firm-side seat, not a replacement for one.
Disclaimer: This article is news reporting and analysis of a private company’s seed financing and product claims, and it is for information only. It is not investment advice, a solicitation to buy or sell securities, or legal advice on fund formation, side letters, MFN elections or any other matter. Readers who are considering an investment, a software contract or a change to fund counsel should speak with a qualified investment adviser and a licensed funds lawyer who can review their own documents. Figures, customer metrics, round terms and product status are those given by the companies, investors and industry bodies cited, and they can change.

One UI 9.5 Beta Puts the Galaxy S26 on Last Year’s Clock

DBS Puts a 24/7 USDC Window Inside the Bank

European Startups Head for $81 Billion as First Checks Shrink

US Stocks Lost $1.3 Trillion Before Nvidia’s Beat

Home Depot Bets on Finance Chief Richard McPhail as CEO

Aramco Crash Kills 14 Two Days After Oil Restart

Salah Captained Egypt to Their First World Cup Win

Zelda’s 40th Switch 2 Ships Without a Zelda Game

Apple Labor Day Deals Hide June’s Memory Price Hike

El Niño Puts Israel’s Needed Winter Rain on a Flood Clock
-
 BUSINESS5 months ago
Aramco Crash Kills 14 Two Days After Oil Restart
-
 NEWS6 months ago
Salah Captained Egypt to Their First World Cup Win
-
 GAMING2 months ago
Zelda’s 40th Switch 2 Ships Without a Zelda Game
-
 NEWS3 months ago
Apple Labor Day Deals Hide June’s Memory Price Hike
-
 NEWS4 months ago
El Niño Puts Israel’s Needed Winter Rain on a Flood Clock
-

 GAMING2 months ago
Palworld 1.0.4 Adds Palpedia Search After the 1.0 Launch
-

 NEWS4 months ago
Saudi Visa Routes Split Nigerian Travelers Into Two Speeds
-

 BUSINESS9 months ago
BAE’s 60-Year Saudi Franchise Now Runs Through Taif