
BUSINESS
Ancep Raises $8.5 Million on a Bet Brokers Stay
Creandum and Kleiner Perkins backed Ancep’s $8.5 million bet that brokers will place the commercial risks they now turn away.

London insurtech Ancep raised $8.5 million in a pre-seed round on November 10, 2026, led by Creandum, with Kleiner Perkins and Vicus Ventures in the round.
The money is a wager that commercial insurance brokers keep their hold on the market, and that the profit is in the policies they currently refuse.
Hamid Had Never Backed a European Pre-Seed
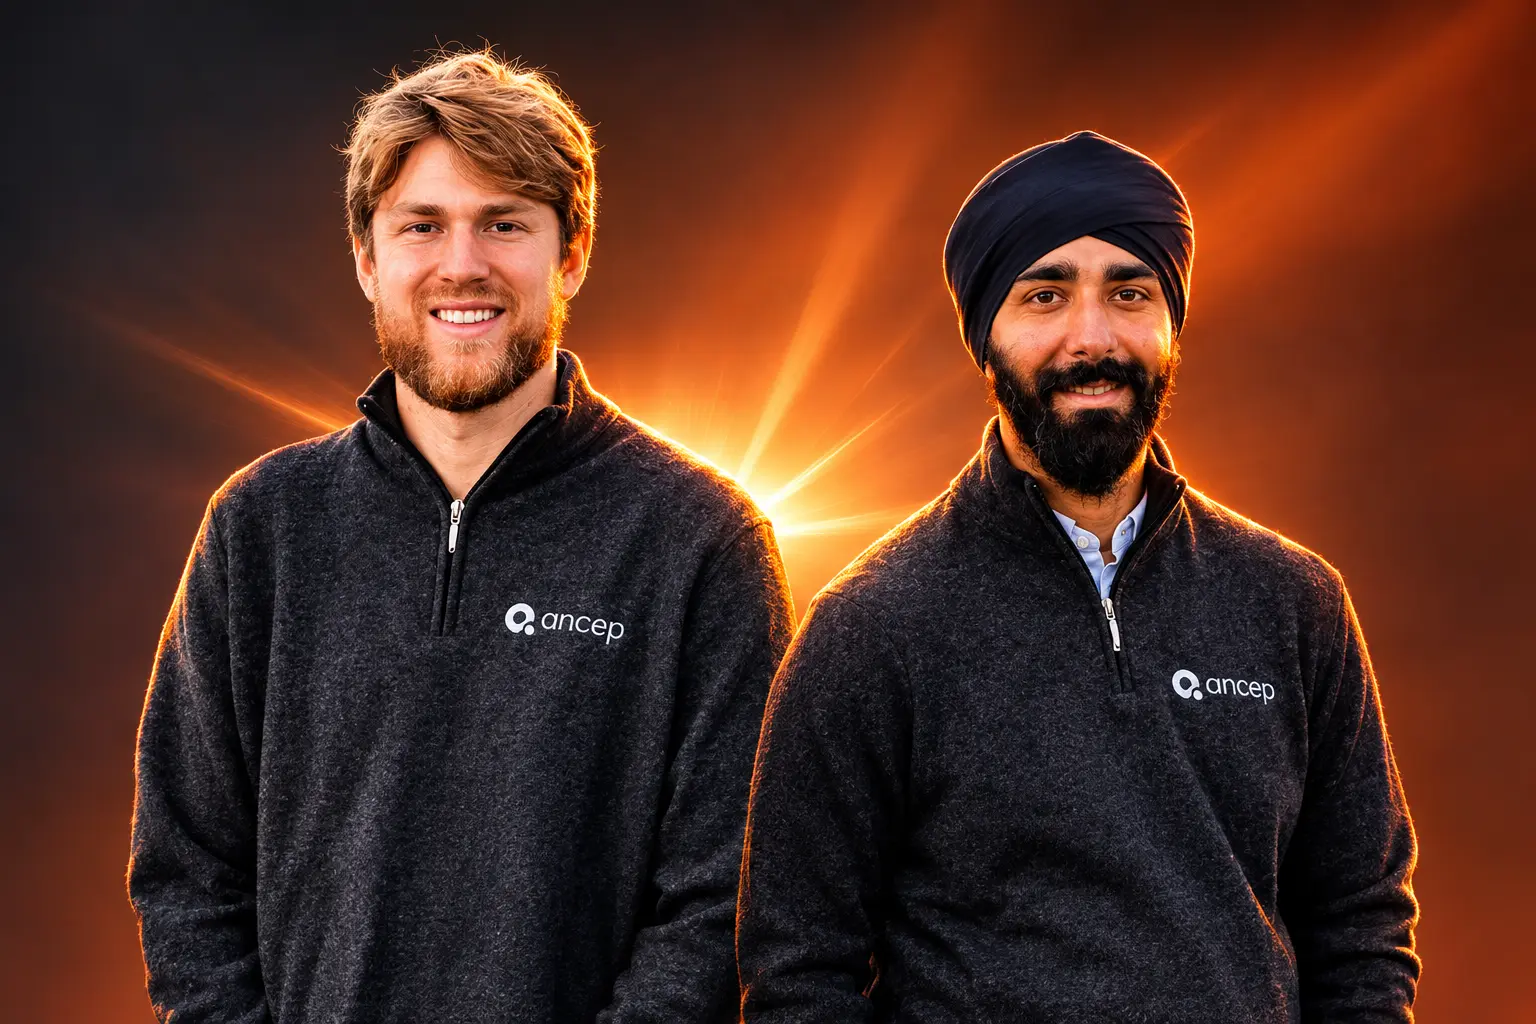
Gagan Khurana, Ancep’s co-founder and chief executive, came out of stealth the same morning. He said the firm’s AI agents are already in daily use at large global brokers, built to place the risks they turn away rather than to sit in a chatbot window.
Insurance is the single most important market on planet Earth, yet it still runs on manual work. Today ancep is coming out of stealth with an $8.5m pre-seed round to change that. Our AI agents are being used daily by the largest global brokers to help them place more risk. pic.twitter.com/9aSkf7Is7V
— Gagan (@GaganSKhurana) November 10, 2026
Mamoon Hamid, a partner at Kleiner Perkins, wrote that he had never invested in a pre-seed company in Europe until he met Khurana and co-founder Jake Turner. That is a heavy cheque for a company founded in 2026, and it is the cleanest read of the round: Hamid is not buying a time-saver for back office staff. He is buying a claim about who still owns the client.
Angel money arrived from Christa Davies, who was chief financial officer of Aon, one of the brokers Ancep wants as a customer, and from operators at OpenAI, Anthropic and Google DeepMind. Raj Singh Sandhu of Vicus Ventures is on the cap table with Hamid and with Simon Schmincke, the Creandum partner who led the round.
Commercial insurance is a $3 trillion market that has absorbed ten years of software promises without much changing inside the largest brokers. Gagan and Jake built something that works within the systems those firms already run, meaning they are live and expanding across lines of business within weeks. Most AI in this market is a bet against the intermediary, but ancep is the first company we have seen that makes it more valuable instead.
Simon Schmincke, Partner, Creandum
Khurana puts the same idea in blunter terms. Plenty of people, he said, are betting brokers get disintermediated. “We think the opposite: brokers have huge leverage, and no chatbot is going to replace it. So we are not building around them, we are building for them, and we are starting with the twenty largest in the world.”
The 30 Percent of Risks Brokers Walk Past
Placing a commercial risk takes roughly the same labour whether the commission is a few hundred pounds or tens of thousands. Below a size line, brokers decline the work or leave it at the bottom of the pile. Ancep’s own math on that pile is the product.
THE REVENUE BROKERS NEVER BOOK
- Declined share: Up to 30 percent of the risks a broker sees fall below the line where the work pays.
- Still placeable: About half of those declined risks could be placed at a profit, Ancep says, if the admin did not eat the commission.
- Unbooked revenue: That gap is 5 to 10 percent of the revenue a large brokerage never records.
- One division: A customer division’s chief operating officer reported a 10 percent revenue rise within six weeks of going live, with no extra headcount.
Those figures are the company’s estimates, not a market census, and the 5 to 10 percent is revenue on smaller slips, not a share of all risks. The pitch still lands because the unit economics are ugly in a way every broker already feels. Rekeying a schedule into five insurer portals costs the same on a thin account as on a fat one, so the thin account loses.
Ancep charges a portion of the value its agents create, so it is paid when the broker is. Khurana said tools sold as time saved and cost cut get stuck in two-year buying cycles. “What we sell is net new revenue.”
Nine Straight Quarters of Falling Commercial Rates
The declined pile gets larger when premiums shrink, because commission rides on the premium. Marsh’s Global Insurance Market Index had global commercial rates down 6 percent in the second quarter of 2026, the eighth quarterly fall in a row. In the third quarter, global commercial insurance rates fell 5%, the ninth decline, with property down 10 percent and casualty still up 1 percent on US litigation pressure.
MARSH COMPOSITE RATE CHANGES, Q3 2026
| Region | Composite change |
|---|---|
| Global | -5% |
| India, Middle East and Africa | -14% |
| Pacific | -12% |
| Latin America and Caribbean | -9% |
| United Kingdom | -8% |
| Canada | -6% |
| Europe | -6% |
| Asia | -6% |
| United States | -1% |
John Donnelly, Marsh’s president of global placement, said buyers were more inclined to keep the premium savings than to buy extra cover. For a broker paid on that premium, the same submission now yields a thinner cheque, which makes the small file even easier to skip.
US survey data from the Council of Insurance Agents and Brokers, summarised for the second quarter, found every account size posted a decrease for the first time in 34 quarters. Large accounts led at a 3.7 percent drop. Medium accounts were down 1.9 percent. Small accounts, the work Ancep wants back on the desk, were down 0.5 percent after a 1.1 percent rise the quarter before, so the price relief that arrived for big risks barely reached the files brokers already treat as a chore.
What the Agents Do on a Placement
The agents read a client’s submission, build the broker’s standard documents from it, and go to insurers for terms by email, portal or API. They run inside Acturis, Applied Epic, AMS360, Salesforce, Dynamics, inboxes and insurer screens, which Ancep says is the difference between a rollout measured in days and one measured in years at firms that already juggle dozens of policy systems.
Only an authorised broker can bind cover. The broking team reviews every output before it takes effect. Each client runs in its own isolated environment, and nothing is pooled or trained on across brokerages without explicit consent. Ancep shows a working prototype within two days of an NDA and deploys one workflow at a time, starting where the pain is worst.
THE JOBS THE AGENTS TAKE FIRST
- Inbox and intake: New mail, PDFs and spreadsheets land in one queue, already read, with mismatches flagged and the client record open.
- Going to market: Each chosen insurer gets the submission in the format that insurer asks for, including portal screens filled as a person would fill them.
- Quote and wording checks: Quotes and policies are lined up on limits, conditions and cover, each figure linked back to the page it came from.
- Chasing and renewals: Missing claims histories and unsigned forms are chased before they stall a file, and last year’s policy is already read when a renewal starts.
Brokers work with the agents in Outlook, on WhatsApp or from a dashboard. Homepage case notes also describe small marine and high-value property files taken from submission to the client report, and cyber quotes pulled from insurer portals so a broker can still write the advice. The bind stays human.
Vienna Brokers Get Their Week Back
The named customer is A.C.I.C. Financial Advisory in Vienna, a specialist credit insurance and surety broker part-owned by RVM, which Ancep calls the fifth-largest insurance broker in Austria. Ancep says the agents are also live with a top 10 UK broker and in the specialty lines of one of the top US brokers. Khurana’s own post went further, saying several of the top 10 largest insurance brokers are already on the system.
A.C.I.C. runs a policy admin system it built in house. Ancep sat on top of that stack, so nothing was ripped out. For each renewal the agents read the expiring policy and the new one, often from different insurers and in different languages, mark every clause change, check it against what the client asked for, and draft a three-part client email in German. The broker reviews it and sends it. Time to value was two weeks. Within the first four weeks, over 50 percent of the team was running the clause by clause renewal checks in Vienna every day.
Credit insurance and surety is specialist work, but a lot of a broker’s week goes on comparing insurer wordings, preparing market submissions, extracting information from large volumes of documents. ancep understood that workflow deeply, rather than trying to sell us generic AI, which is why adoption across the business has been exceptionally high. We did not do this to cut costs but to get our specialists’ time back, and they are now using it to advise clients, expand into new markets and build insurance products we didn’t have the capacity to design previously.
Christoph Zawadil, Managing Director, A.C.I.C. Financial Advisory
That is the operating proof the investors are underwriting: a specialist shop that did not fire people, took more clients, and spent the recovered hours on advice and new products. If the same pattern holds inside a Marsh, Aon or WTW specialty desk, the 5 to 10 percent Ancep talks about becomes a line on a public broker’s income statement.
Two Oxford Founders Who Already Sold This Motion
Khurana and Turner met at Oxford and started Ancep in 2026 after a year together at Scope AI, which sells AI into testing, inspection and certification. Khurana ran sales and Turner ran engineering as revenue went from almost nothing to $2 million in under a year, after which Scope raised a $20 million Series A from Index Ventures. Ancep says it builds to the same standard it used in a trade where an error can put physical infrastructure at risk.
Khurana arrived in Britain from Kabul as a refugee in 2001 and sold on his father’s stall in Shepherd’s Bush Market before McKinsey, where insurance work first put him in front of brokers. Turner was the first engineer at the quantum computing firm QuantrolOx and interviewed more than 50 brokers in depth on an earlier venture. The pair are hiring against the new funds, and Wilson Sonsini advised on the round.
The Twenty Largest Brokers Are the Whole Plan
Ancep is not selling a marketplace that cuts the broker out, and it is not starting with independent high-street shops. The stated target is the twenty largest brokers in the world, the firms that already run the messy systems Schmincke described, and that already see the small files they do not staff. Hamid’s exception at Kleiner Perkins, Davies’s cheque after sixteen years inside Aon, and Creandum’s lead all point at that same account list.
The next test is whether those desks keep signing off agent output once the files are no longer a Vienna credit book or a single specialty line. Until then the wager is on the table at $8.5 million: the broker stays the trust layer, and the rejected pile is where the new premium is.

One UI 9.5 Beta Puts the Galaxy S26 on Last Year’s Clock

DBS Puts a 24/7 USDC Window Inside the Bank

European Startups Head for $81 Billion as First Checks Shrink

US Stocks Lost $1.3 Trillion Before Nvidia’s Beat

Home Depot Bets on Finance Chief Richard McPhail as CEO

Aramco Crash Kills 14 Two Days After Oil Restart

Salah Captained Egypt to Their First World Cup Win

Zelda’s 40th Switch 2 Ships Without a Zelda Game

Apple Labor Day Deals Hide June’s Memory Price Hike

El Niño Puts Israel’s Needed Winter Rain on a Flood Clock
-
 BUSINESS5 months ago
Aramco Crash Kills 14 Two Days After Oil Restart
-
 NEWS6 months ago
Salah Captained Egypt to Their First World Cup Win
-
 GAMING2 months ago
Zelda’s 40th Switch 2 Ships Without a Zelda Game
-
 NEWS3 months ago
Apple Labor Day Deals Hide June’s Memory Price Hike
-
 NEWS4 months ago
El Niño Puts Israel’s Needed Winter Rain on a Flood Clock
-

 GAMING2 months ago
Palworld 1.0.4 Adds Palpedia Search After the 1.0 Launch
-

 NEWS4 months ago
Saudi Visa Routes Split Nigerian Travelers Into Two Speeds
-

 BUSINESS9 months ago
BAE’s 60-Year Saudi Franchise Now Runs Through Taif