
BUSINESS
A Payments Veteran Backs NABU’s €1.1 Million KYC Bet
NABU raises €1.1 million as former CCV owner Enny van de Velden bets AI can prefill merchant KYC before the EU’s 2027 AML rulebook.

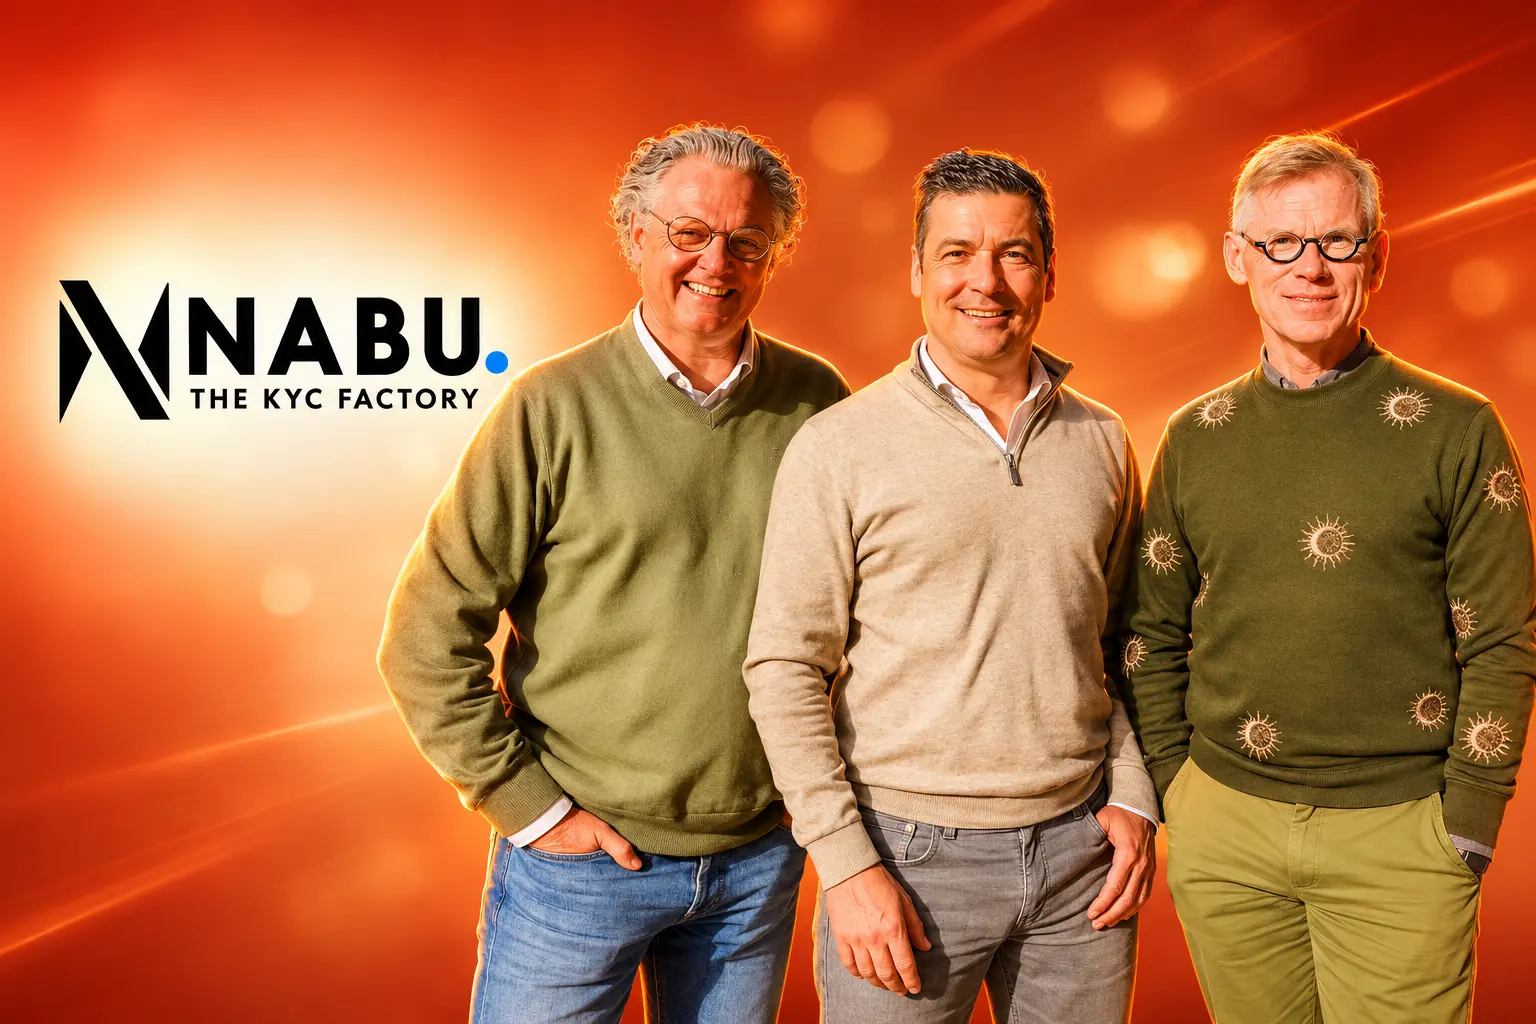
NABU has raised €1.1 million from business angels, including former CCV owner Enny van de Velden, to automate KYC and AML checks. The Ghent firm, Nabu Tech BV, was founded in 2025 by Karel-Lodewyck Lefere, Bart Vermeulen and Koen Handekyn, and it sells AI agents that build customer files from company registers instead of email attachments.
Van de Velden spent years running CCV, the Benelux payments group Fiserv bought in March 2025. In July 2026 Dutch supervisors published a €2.65 million fine on that group after thousands of merchants sat outside its monitoring system. Her cheque is a wager that the next fight in payments is the customer file, not another terminal.
The KYC Factory Built for Merchants
NABU’s own site does not lead with universal banks. It lists acquirers, payment facilitators, independent sales organisations and private funds, and it pitches “deep KYC” as a way to onboard and watch merchants in minutes rather than weeks. Lefere, the chief executive, and his co-founders came out of payments, and the product is built around a VAT number, a company register extract and a living merchant file, not a consumer selfie flow.
The company says the software pulls records from official registers and databases, including Dun & Bradstreet, then opens a file and asks only for the extra papers still missing. It also watches those files for later changes and automates parts of the reports that go to financial regulators and tax authorities. Final yes-or-no calls stay with staff, NABU says, which is the line most vendors use when they sell AI into a supervised process.
That buyer list matters more than the headline about “regulated businesses.” Banks already rent screening stacks. The firms that actually take this call are payment companies that must know their merchants, and funds that must know their investors, with small compliance teams and a supervisor that can fine them for files that never loaded.
What a VAT Number Replaces in the KYC File
Lefere’s short version of the product is blunt. Give the platform a VAT number, he said on a FinTech Belgium Media podcast in March, and it fills about 90 percent of the merchant profile: who you are, where you sit, the company, the website. The remaining slice is the documents a register cannot see. NABU separately says the same tooling can automate up to 90 percent of customer due diligence tasks, a different claim on a wider pile of work, while staff still take the last decision.
He has used one onboarding story as a speed check: an elderly investor, he said, finished an investment-fund process in 10 minutes. That is a vendor anecdote, not a measured average, but it is the outcome the raise is meant to industrialise. The legal entity behind the pitch is Nabu Tech BV in Ghent, company number BE 1024.614.661.
WHERE THE FILE IS SUPPOSED TO COME FROM
- Official records: Company registries, ownership databases, sanctions lists and watchlists, so a merchant is not asked to retype what the state already holds.
- Structured data: Filings, licences and internal blacklists that sit in formats a rules engine can read without a scan of a PDF inbox.
- Unstructured data: Websites, social pages and reviews, which the company says its agents read to build a risk view that a register extract will not show.
The gap Lefere keeps naming is not a missing algorithm. It is the habit of making the customer upload, again, data that already exists, then sending the sensitive leftovers over email.
Much of that data already exists. It’s in national company registers, in public sources or on your electronic ID. And yet customers still have to supply everything themselves. On top of that, sensitive documents are often still exchanged by email. That’s outdated and unsafe, and that’s exactly what we want to change.
Karel-Lodewyck Lefere, co-founder and CEO of NABU
If that prefill holds up in audit, a PayFac or a small fund can run a file that looks closer to a bank’s without hiring a bank’s operations floor. If it does not, the firm still owns the decision, and the supervisor still owns the fine.
The Founders Learned the File Problem in Payments
Lefere has said that he and his co-founders built their working lives in payments, not in a general-purpose software shop. Vermeulen is chief revenue officer. Handekyn is chief technology officer. The three founded NABU in 2025 and pointed the first sales motion at the same merchant stack they already knew: acquirers, facilitators, ISOs, then private equity and venture funds that now sit in the same due-diligence net.
A Ghent hiring notice this autumn still named PE and VC funds, leasing firms, financial institutions and payment providers as the accounts a new business-development manager would chase, “ahead of the EU’s new AML rulebook.” That is a seed-stage company talking like a vertical tool, which is also why a payments angel fits the cap table better than a general AI fund.
Van de Velden is the name the raise chose to print. She joined CCV in 2012, became chief commercial officer and chair of the board from 2016, and left those operating roles on 1 January 2024, with a planned move toward the supervisory board after a cooling-off period. CCV started in 1958 under her father, Cor van de Velden, as Computercentrum C. van de Velden, and grew into a Benelux payments group. Fiserv announced the takeover of the family business in March 2025. She described the sale, on her own account, as a win for both sides and a hard goodbye.
DNB’s File on 4,200 Unwatched Merchants
The operational failure that now sits next to her cheque is not a NABU case. It is CCV’s. De Nederlandsche Bank said on 13 July 2026 that it had imposed a €2.65 million administrative fine on payment institution CCV Netherlands B.V. because the firm failed to monitor transactions on an ongoing basis, in breach of Section 3(2) of the Dutch Anti-Money Laundering and Anti-Terrorist Financing Act, the Wwft.
DNB’s published summary is specific about the plumbing. For over two years the monitoring system was not fully and promptly fed with all merchant transactions. For 23 months the firm did not properly load transaction profiles for 4,200 merchants outside transaction monitoring, about 8 percent of the book. Alerts were closed without a proper reason, or sent to a desk that did not review them, and some were closed in bulk. DNB started from a basic fine of €2.5 million, raised it because CCV had already been fined for the same section of the Wwft, then cut it back after CCV filed a recovery plan it is still running.
WHAT DNB SAID IT FOUND AT CCV
| Item | DNB finding |
|---|---|
| Firm | CCV Netherlands B.V., a payment institution |
| Published | 13 July 2026 |
| Fine | €2.65 million |
| Legal basis | Section 3(2) of the Wwft |
| Merchants missed | 4,200, about 8 percent of the book, for 23 months |
| System feed | Not fully and promptly loaded for over two years |
| Alerts | Closed without enough reason, including bulk closures |
| Penalty path | Basic €2.5 million, raised as a repeat breach, then reduced for a recovery plan |
Van de Velden was no longer in the operating chair when DNB published that decision, and the group was already under Fiserv. The fine still describes the exact workload NABU is selling into: merchant profiles that must load, stay current, and leave an audit trail when an alert is closed. The published amount is more than twice NABU’s entire round.
Payment institutions are gatekeepers under the Wwft, DNB said, and they have to watch every transaction after a merchant is accepted. When the feed breaks, criminal money can move on rails that look ordinary. That is a software and data problem as much as a policy problem, which is why a KYC factory that claims to keep the file alive is a logical cheque for someone who has already sat inside a merchant acquirer.
The Rulebook That Binds From 10 July 2027
NABU is timing the raise against a date that is already in Union law. Regulation (EU) 2024/1624, the Anti-Money Laundering Regulation adopted on 31 May 2024 and published on 19 June 2024, applies from 10 July 2027 for almost every obliged entity. Article 90 of that text is short: the regulation is binding in full and directly applicable in all member states, with a later start of 10 July 2029 only for the football agents and professional clubs listed in Article 3.
Because it is a regulation, firms do not wait for a local rewrite of an old directive. Customer due diligence, beneficial ownership at a common 25 percent ownership line, and refresh cycles (yearly for high-risk customers, at least every five years for others, in the rulebook’s own timetable) will read the same in Ghent, Amsterdam and Luxembourg City. Lefere puts the pool of European companies that must run these checks at up to 100,000. That figure is his, not a census in the regulation, and it is the demand curve the seed round is written against.
THE DATES AROUND NABU’S CHEQUE
- 1958: Cor van de Velden founds the business that becomes CCV, later a Benelux payments group.
- 2012: Enny van de Velden joins CCV; she becomes CCO and chair of the board in 2016.
- 1 January 2024: She leaves those operating roles at CCV.
- March 2025: Fiserv takes over CCV; NABU is founded the same year in Ghent.
- 26 March 2026: Mastercard announces Lighthouse Belgium, a three-month startup programme with no equity take.
- 13 July 2026: DNB publishes the €2.65 million CCV monitoring fine.
- 17 November 2026: NABU raises €1.1 million from angels including van de Velden.
- 10 July 2027: The EU AML regulation starts to apply to almost every obliged entity.
The people on the hook are not only credit institutions. Article 3 of the regulation also pulls in financial institutions (including crypto-asset service providers), auditors, accountants, tax advisers, certain lawyers and notaries, trust and company service providers, estate agents, listed traders in high-value goods, and gambling operators, among others. Payment firms stay with national supervisors unless they are large enough and risky enough for the new EU Anti-Money Laundering Authority to pick them for direct watch. Most of NABU’s named buyers will never see that direct list. They will still have to show a file.
Mastercard Put NABU in a 12-Week Cohort
The other door the company is walking through is a card network, not a venture firm. On 26 March 2026 in Waterloo, Mastercard launched the Mastercard Lighthouse Belgium programme, a local track meant to put early Belgian startups in front of partners and mentors without taking shares. Each cohort takes 6 to 8 companies for a three-month curriculum. The first Belgian intake includes NABU among six names, and NABU has been posting from that room, including a kickoff at Mastercard’s European headquarters.
Benjamin Dessy, Mastercard’s country manager for Belgium and Luxembourg, said at launch that the point was practical: help firms that start in Belgium find a European path while they stay tied to the local market. The programme is free. Selected companies can be pushed on toward Mastercard Start Path, the global scale-up track. For a KYC vendor that lives on acquirers and PayFacs, a card-network address book is a distribution channel that €1.1 million cannot buy on its own.
NABU says the new money goes into the platform and into sectors beyond the first payments and funds wedge, including insurance, legal services and payments more broadly. It is also starting work in the Netherlands and Luxembourg, with a stated aim of covering the Union. Those are seed promises, not booked revenue, and they sit on the same 2027 clock as every other obliged firm in those countries.
A Seed Cheque Against Nine-Figure Rivals
The honest scale of the bet is the cap table. Disclosed funding tallies put Unit21, a US monitoring and case platform, at $92 million. Sardine, which sells fraud and AML together, is at $171 million, after a $70 million Series C in February 2025 and a $25 million add-on in May 2026. ComplyAdvantage, the London screening specialist, has raised at least $88 million. Those vendors sell into banks and larger fintechs that already have compliance heads and procurement. NABU is trying to be cheap and fast enough for the long tail that those platforms often price out.
HOW THE CHEQUE COMPARES
| Company | Disclosed capital | Centre of gravity |
|---|---|---|
| NABU | €1.1 million (angels, November 2026) | Merchant and fund KYC, Benelux first |
| ComplyAdvantage | At least $88 million | Sanctions, PEP and adverse-media screening |
| Unit21 | $92 million | Fraud and AML operations, cases, filings |
| Sardine | $171 million | Device fraud plus AML for fintechs |
A round this small cannot light up 27 company registers, staff a 24-hour alert desk, and still look cheap. It can, if the VAT-to-file trick works, make a Dutch or Belgian acquirer stop collecting the same PDF twice. That is a narrower product than the wire copy implied, and it is the only product €1.1 million can actually fund before 10 July 2027.
Van de Velden already lived the merchant side of that problem inside CCV. DNB has now put a public price on what happens when merchant profiles never load. NABU is the small, local answer she has chosen to back, with a card-network cohort as a second door, and with a Union rulebook that will not wait for a Series B.

One UI 9.5 Beta Puts the Galaxy S26 on Last Year’s Clock

DBS Puts a 24/7 USDC Window Inside the Bank

European Startups Head for $81 Billion as First Checks Shrink

US Stocks Lost $1.3 Trillion Before Nvidia’s Beat

Home Depot Bets on Finance Chief Richard McPhail as CEO

Aramco Crash Kills 14 Two Days After Oil Restart

Salah Captained Egypt to Their First World Cup Win

Zelda’s 40th Switch 2 Ships Without a Zelda Game

Apple Labor Day Deals Hide June’s Memory Price Hike

El Niño Puts Israel’s Needed Winter Rain on a Flood Clock
-
 BUSINESS5 months ago
Aramco Crash Kills 14 Two Days After Oil Restart
-
 NEWS6 months ago
Salah Captained Egypt to Their First World Cup Win
-
 GAMING2 months ago
Zelda’s 40th Switch 2 Ships Without a Zelda Game
-
 NEWS3 months ago
Apple Labor Day Deals Hide June’s Memory Price Hike
-
 NEWS4 months ago
El Niño Puts Israel’s Needed Winter Rain on a Flood Clock
-

 GAMING2 months ago
Palworld 1.0.4 Adds Palpedia Search After the 1.0 Launch
-

 NEWS4 months ago
Saudi Visa Routes Split Nigerian Travelers Into Two Speeds
-

 BUSINESS9 months ago
BAE’s 60-Year Saudi Franchise Now Runs Through Taif