
BUSINESS
India’s Tax Portal Now Shows Foreign Assets on AIS
India’s income tax portal now shows CRS foreign assets on AIS, turning partner files into a FAST-DS match list before 31 December 2026.

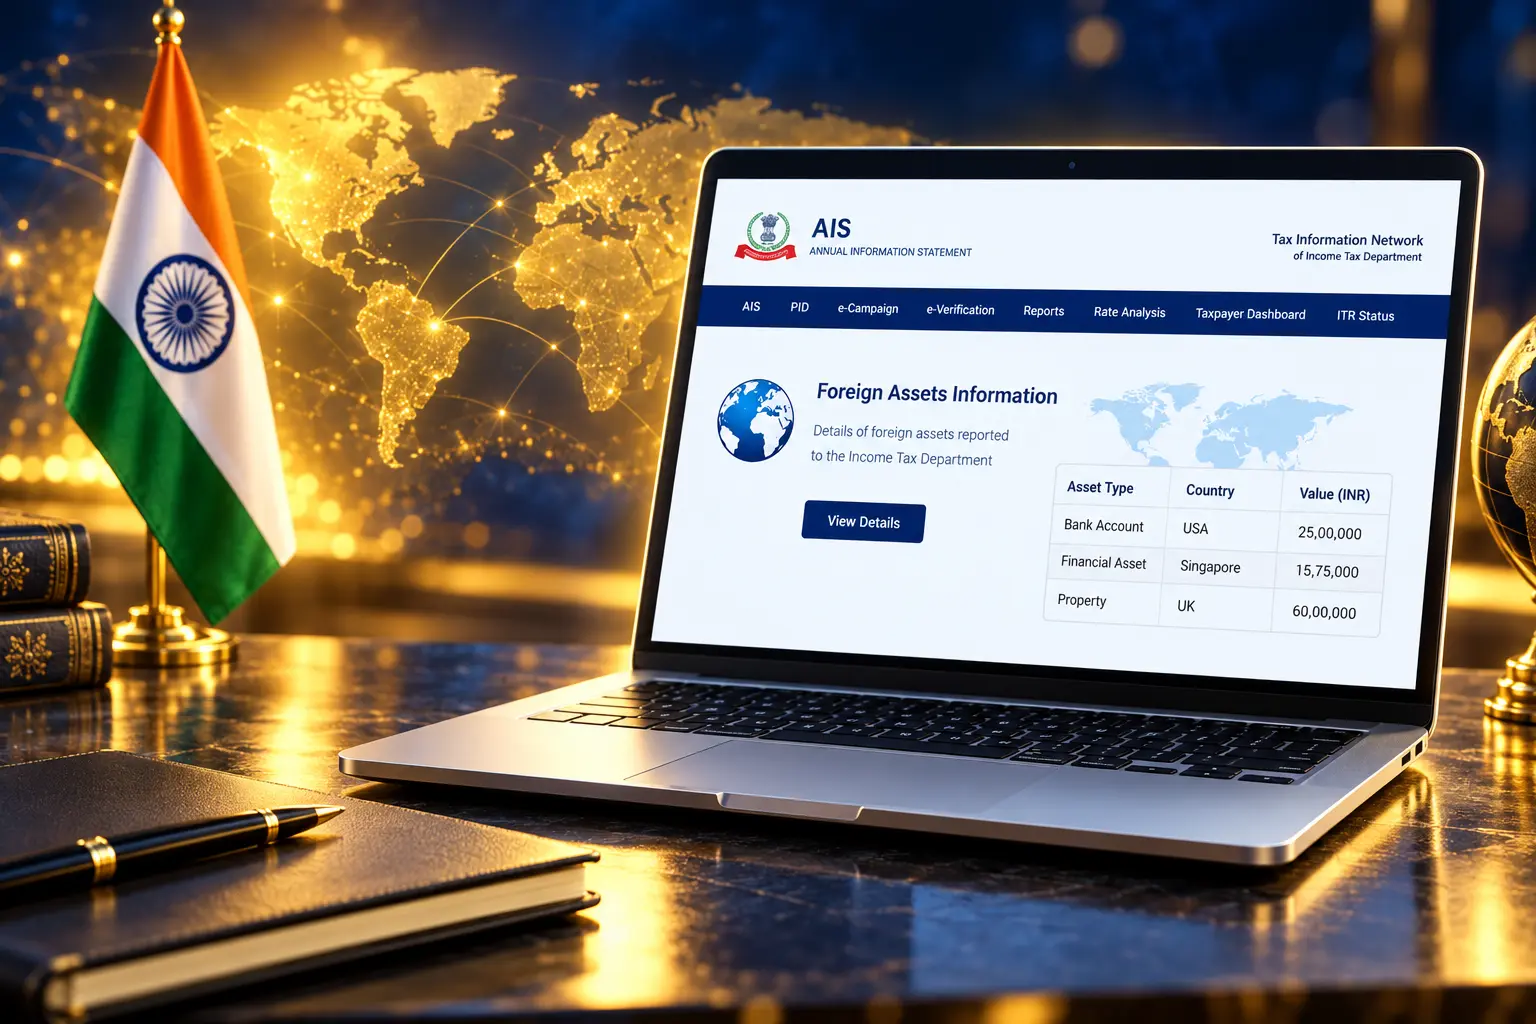
India’s income tax portal now shows foreign bank accounts, investments and overseas income inside the Annual Information Statement. Eligible users can download calendar years 2022, 2023 and 2024 as a PDF from the Compliance Portal.
The Central Board of Direct Taxes calls the feed a filing aid for assessment year 2026-27, not an investigation. The harder consequence is a match file: partner-country data now sits where a taxpayer can see it, and where the department can later stack it against Schedule FA, while a paid disclosure window runs to 31 December 2026.
The Board Put CRS Files on the Taxpayer Screen
The board authorised that upload on 8 July 2026 in an order signed by Dr. Indu Bala, deputy secretary in the ITA-II wing. The Directorate General of Income-tax (Systems) in Delhi has 90 days from the end of the month of receipt to put Automatic Exchange of Information files into the Annual Information Statement as Form No. 168, under section 239 of the Income-tax Act, 2025 and Rule 245(2).
Grant Thornton Bharat wrote that those inbound files were used mainly inside the department for risk work. Putting them on AIS gives the taxpayer a copy of part of the same pack. The board’s own note says India already receives financial information on its tax residents from over 100 partner jurisdictions, and that AEOI data for the prior calendar year starts arriving each September.
SMS and email alerts went out with the new report, telling people to report foreign assets and foreign income in the return for assessment year 2026-27. The same note points users to Kar Saathi, the portal’s virtual assistant, for form choice and Schedule FA questions. The language is polite. The sequence is not accidental.
THE JULY-TO-DECEMBER CLOCK
- 8 July 2026: CBDT order F.No. 225/73/2025-ITA-II authorises AEOI uploads into AIS as Form No. 168.
- July 2026: The board enables a Foreign Assets Information report on the Compliance Portal for calendar years 2022, 2023 and 2024.
- 14 August 2026: Notification No. 114/2026, G.S.R. 732(E), notifies the FAST-DS Rules.
- 16 August 2026: The Foreign Assets of Small Taxpayers Disclosure Scheme, 2026, opens for Form 1 filings.
- 23 October 2026: Officials say a high-level meeting backs sharing extra overseas-asset information with some taxpayers, where that is allowed.
- 31 December 2026: Last date to file Form 1 under FAST-DS, and the belated-return date for assessment year 2026-27.
Users who want to view foreign-asset information in AIS log into the e-Filing account, open AIS, go to Reports, pick Foreign Assets Information, choose a calendar year and download the PDF. The board says only the PAN holder can see that file through a secure login.
What the Foreign Assets Report Lists
The PDF is a year-wise extract of what partner tax authorities sent under CRS and FATCA, not a full inventory of everything a resident owns abroad. It can include foreign bank and custodial accounts, some investments, interest, dividends and other specified financial income. It does not replace the return, and it does not list every house, trust or closed account a filer still has to disclose.
WHAT THE PDF SHOWS
| Item | On the AIS foreign-asset PDF | Still the taxpayer’s job |
|---|---|---|
| Foreign bank and custodial accounts | If a partner jurisdiction reported them under CRS or FATCA | Full Schedule FA line, including peak and closing balances |
| Interest, dividends, specified financial income | If received in the AEOI pack | Schedule FSI, plus tax relief claims where a treaty applies |
| Overseas shares, funds, insurance cash values | Only if the foreign institution reported them | Report even when the PDF is blank |
| Immovable property abroad | Generally outside CRS financial-account files | Schedule FA still requires it for a resident and ordinarily resident |
| Joint, inherited or closed accounts | May be missing, mis-tagged or stuck on an old name | Disclose and keep statements, even if AIS is silent |
| Calendar year 2025 | Board said it would show the data once received in September or October 2026 | Schedule FA for that year still follows 1 January to 31 December 2025 |
Names, account numbers and balances can drift because of currency conversion and reporting cycles. Dates on the PDF may not match a local bank statement. Feedback can go back through the AIS tool, but a blank line is not permission to omit the asset.
A Disclosure Window That Closes on 31 December
The same summer, Chapter IV of the Finance Act, 2026, opened FAST-DS as a one-time, online declaration for specified foreign assets and foreign income. The rules that took effect in August set 16 August 2026 as day one and 31 December 2026 as the last date. No Form 1 can be filed after that. The valuation date is 31 March 2026, and every figure has to be in rupees.
Finance ministry officials said about 1,100 taxpayers had filed by late October 2026. The department’s own account then pushed Form 1 in public, stressing a flat fee track for some already-explained holdings.
Have you disclosed your foreign assets in your ITR?
✅ FAST-DS 2026 offers eligible taxpayers a one-time opportunity to declare previously unreported foreign assets.
✅ Flat fee of ₹1 lakh for eligible foreign assets valued up to ₹5 crore, subject to conditions.Act now, if… pic.twitter.com/bcqNg0TVdz
— Income Tax India (@IncomeTaxIndia) October 27, 2026
Officials also said the on-screen report shows only CRS and FATCA files, and that other multilateral packs have been held back because of risk and non-disclosure commitments. After the 23 October meeting, they said some of that extra information could still be shared with the people it concerns, so they can use the scheme. That is how a portal that lists bank accounts can sit next to outreach about houses in the UAE, which CRS was not built to map.
THE TWO FAST-DS PRICES
| Category | What it covers | Cap on 31 March 2026 | Amount payable |
|---|---|---|---|
| 1. Untaxed foreign asset or income | An undisclosed asset abroad, or foreign income that was taxable in India and was not offered | ₹1 crore combined | 30% tax plus an equal amount, so 60% of the declared value or income |
| 2. Explained asset, missed schedule | An asset bought from income earned as a non-resident, or from income already taxed in India, but left out of the right schedule | ₹5 crore | A flat fee of ₹1 lakh |
The official Form 1 and the scheme FAQs walk through mixed cases. Shares bought from taxed money can sit in Category 2 for the ₹1 lakh fee, while an untaxed dividend on those shares sits in Category 1; the board’s worked example puts that dividend slice at ₹2.4 lakh. Form 1 can hold several assets. Form 2, which sets the sum payable, is due within one month from the end of the month of filing. Form 3 then records payment within four months from the end of the month of Form 2. Amounts paid are not refundable.
A valid declaration is meant to give immunity from further assessment, penalty and prosecution under the Black Money (Undisclosed Foreign Income and Assets) and Imposition of Tax Act, 2015, for what was declared. People who already paid tax on the money and only skipped a schedule are being asked to buy that paper with ₹1 lakh. That fee is why some filers would rather wait for a notice than regularise a leftover foreign account they can already explain. Thin uptake at about 1,100 filings fits that resistance more than it fits a rush of hidden Swiss accounts.
Leftover Foreign Accounts After an NRI Return
Schedule FA applies to a resident and ordinarily resident. A non-resident, or a resident but not ordinarily resident, does not file that schedule. FAST-DS looks at a different year: the year the income arose, or the year the asset was acquired, not the date of the declaration. A person who is RNOR now can still be in the scheme for a year when they were resident.
That split hits people who came back to India with a UK ISA, a US brokerage, a Dubai current account or employee stock still vesting. For two or three years they may have been RNOR and under no FA duty. Once they become ordinarily resident, one day of holding in the calendar year is enough to require a return with Schedule FA, even if Indian income is below the basic exemption. The new PDF will surface the accounts a foreign bank has already tagged as Indian-resident. It will not explain the RNOR years, joint names or an account closed after the reporting date.
Officials said the department had begun contacting some taxpayers with residential and commercial property in the UAE. Industry estimates cited in that briefing put Indian property buying in the emirate in the tens of billions of dirhams a year. Those bricks will not necessarily appear in the AIS financial-account extract, which is why a “check your PDF” message and a property nudge can arrive as two different letters about the same person.
Schedule FA Still Has to Match the PDF
Schedule FA runs on the calendar year, not the April-to-March tax year. For the return of financial year 2025-26 (assessment year 2026-27), the schedule is meant to list assets held from 1 January 2025 to 31 December 2025. Bank lines ask for the peak balance during that year, the closing balance on 31 December, and gross interest. That peak figure is a frequent miss, and it will not always equal the year-end number a CRS file carries.
This taxpayer-centric initiative has been undertaken to facilitate, and not to investigate, taxpayers in meeting their compliance obligations.
Central Board of Direct Taxes, AIS foreign-asset note, July 2026
The same note is blunt on the legal duty. Information in AIS “does not constitute a complete or exhaustive record,” and taxpayers must still report all foreign assets and foreign-source income in Schedule FA and Schedule FSI “irrespective of whether such assets or income are reflected in AIS.”
THE RECONCILIATION LIST
- Download each year: Pull the Foreign Assets Information PDF for 2022, 2023 and 2024 and keep the files with the return papers.
- Build a register: List every overseas bank, broker, fund, ESOP or RSU, pension, insurance cash value, trust interest and property, including joint and closed accounts.
- Match peaks, not just closes: Schedule FA wants the calendar-year peak and the 31 December close; CRS often sends a year-end value.
- Separate status years: Mark RNOR or non-resident years so a live account is not treated as an FA miss for a year when the schedule did not apply.
- Use FAST-DS while it is open: Where a past return omitted an asset that now sits in AIS, Form 1 is the time-bound route the board has put on the same portal.
- Keep foreign tax proof: Treaty relief still needs returns, withholding certificates and rupee workings, which AIS will not attach.
An updated return under section 139(8A) remains a separate path for some older years, at extra tax of 25 to 70 percent of the tax and interest, depending on delay. It is not a substitute for FAST-DS, and it cannot be used to chase a refund. Where FAST-DS fits, waiting for ITR-U after 31 December 2026 is a more expensive way to correct the same omission.
How the Rs 10 Lakh Penalty Still Applies
Under the Black Money Act, a resident who is not RNOR can face a ₹10 lakh penalty for failing to file a return that should have included a foreign asset, or for filing a return that leaves the asset out or gets it wrong. Tax on undisclosed foreign income and assets can carry a further penalty of three times the tax. Wilful defaults can move into prosecution sections. That stack is what FAST-DS is selling immunity from, for people who qualify and pay on time.
PENALTIES STILL ON THE BOOKS
- ₹10 lakh a year: Black Money Act penalty for a missed or wrong foreign-asset line in a resident (not RNOR) return.
- ₹20 lakh de minimis: From 1 October 2024, that penalty is not meant to apply where aggregate foreign assets other than immovable property stay at ₹20 lakh or less; reporting in the return is still required.
- ₹1 lakh FAST-DS fee: Category 2 price for explained assets up to ₹5 crore that never reached the right schedule.
- 60% FAST-DS levy: Category 1 price on untaxed foreign assets or income up to ₹1 crore, valued on 31 March 2026.
CBDT has also said prosecution under the Black Money Act should not start where the related penalty is not imposed on those small-value, non-property holdings. That is relief on the criminal step, not a pass on Schedule FA. A leftover current account with a modest balance can still be a reporting miss. A Dubai flat sits outside that ₹20 lakh cushion because it is immovable property.
FAST-DS values a foreign bank account by aggregating deposits from opening to the valuation date, with rules to avoid counting the same money twice when it was withdrawn and put back. That is a harsher yardstick than a 31 December screenshot, and it is another reason a “small” account can look larger on Form 1 than it does on AIS.
More Than 100 Jurisdictions Feed the Same Screen
India was in the OECD’s first CRS exchanges in 2017, in a cohort of 49 jurisdictions. The board’s CRS guidance now puts participation at over 120 jurisdictions as of 2026, with India exchanging annually. The OECD’s 2025 AEOI peer-review update recorded 171 million accounts exchanged in 2024, worth nearly EUR 13 trillion, across 116 jurisdictions that had started sending files.
Those volumes are why a PDF on the Compliance Portal is not a small product tweak. Once a foreign bank has reported an Indian resident, the cheapest next step for Delhi is to show the taxpayer the line and wait for Schedule FA, Form 1 or a mismatch. The board can still say, correctly, that the report is incomplete. Property, some trusts and data held under other treaties may never appear there, and 2025 files were only due into the system in September or October 2026.
The window to buy immunity under FAST-DS still ends on 31 December 2026, on the same date as belated returns for assessment year 2026-27. After that, the AIS line remains, the partner files keep coming, and the ₹10 lakh penalty on a missed foreign-asset disclosure does not need a complete PDF to apply.
Disclaimer: This article is news reporting and analysis of publicly described tax-portal and disclosure rules. It is informational only and is not tax, legal or financial advice, a recommendation to file or not file Form 1, or a calculation of anyone’s tax, penalty or fee. Readers should consult a qualified chartered accountant or tax lawyer who can review their residential status, foreign statements and past returns before they disclose, pay or amend a filing. Figures, scheme dates and portal contents reflect the official notes and statements cited here and can change as CBDT uploads further calendar years or amends FAST-DS practice.

One UI 9.5 Beta Puts the Galaxy S26 on Last Year’s Clock

DBS Puts a 24/7 USDC Window Inside the Bank

European Startups Head for $81 Billion as First Checks Shrink

US Stocks Lost $1.3 Trillion Before Nvidia’s Beat

Home Depot Bets on Finance Chief Richard McPhail as CEO

Aramco Crash Kills 14 Two Days After Oil Restart

Salah Captained Egypt to Their First World Cup Win

Zelda’s 40th Switch 2 Ships Without a Zelda Game

Apple Labor Day Deals Hide June’s Memory Price Hike

El Niño Puts Israel’s Needed Winter Rain on a Flood Clock
-
 BUSINESS5 months ago
Aramco Crash Kills 14 Two Days After Oil Restart
-
 NEWS6 months ago
Salah Captained Egypt to Their First World Cup Win
-
 GAMING2 months ago
Zelda’s 40th Switch 2 Ships Without a Zelda Game
-
 NEWS3 months ago
Apple Labor Day Deals Hide June’s Memory Price Hike
-
 NEWS4 months ago
El Niño Puts Israel’s Needed Winter Rain on a Flood Clock
-

 GAMING2 months ago
Palworld 1.0.4 Adds Palpedia Search After the 1.0 Launch
-

 NEWS4 months ago
Saudi Visa Routes Split Nigerian Travelers Into Two Speeds
-

 BUSINESS9 months ago
BAE’s 60-Year Saudi Franchise Now Runs Through Taif